Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

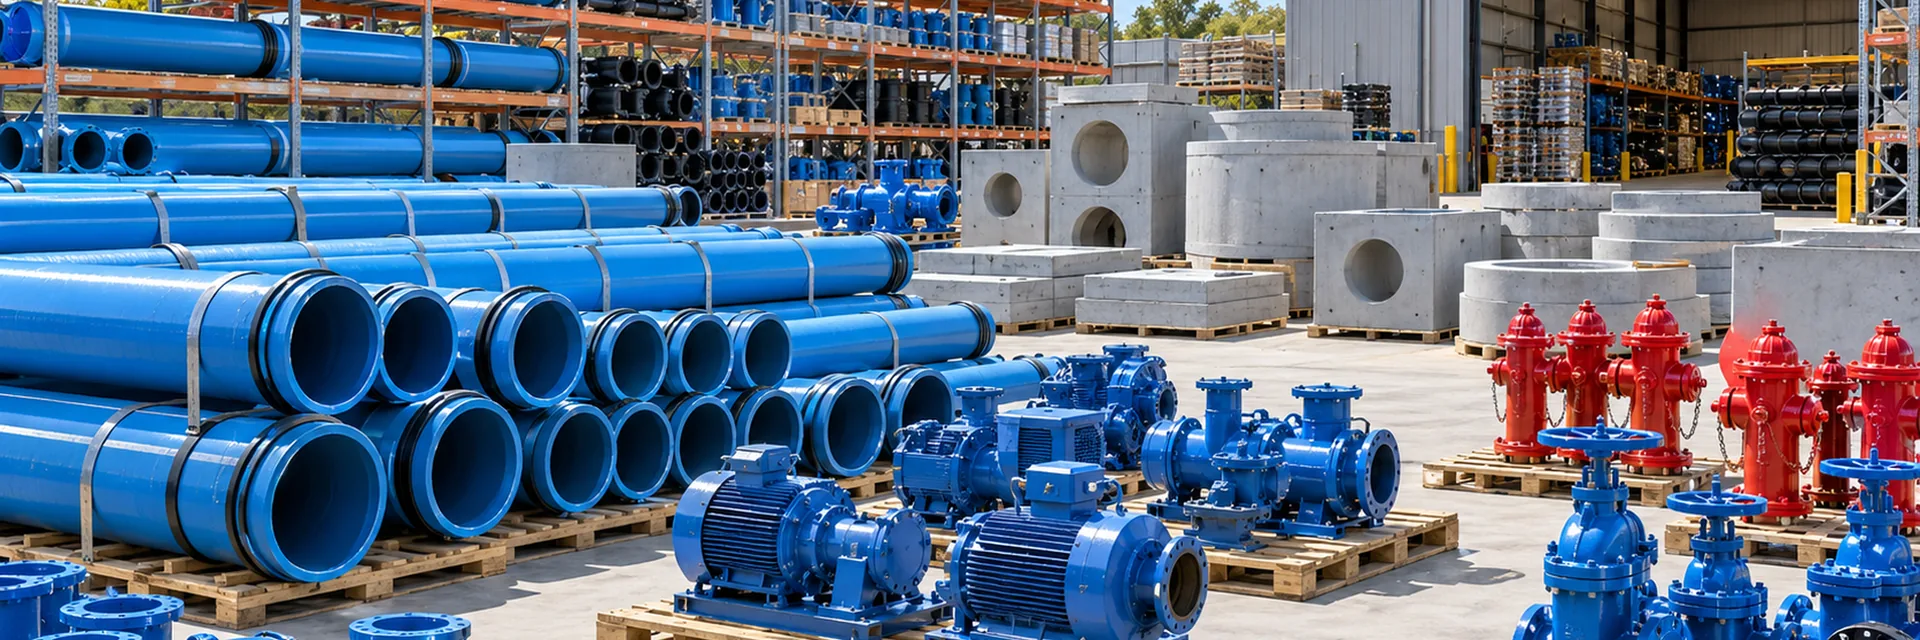
A waterworks supply yard stacked with large-diameter blue water main pipe, flanged valves, pumps, fire hydrants and precast concrete vaults — pump waterworks supplier insurance california

California commercial insurance

Pump & Waterworks Supplier Insurance CA

844-97-USAVE

Pump and waterworks suppliers serve plumbing, municipal, industrial and infrastructure projects with pumps, valves, controls, pipe and specialty equipment.

  • Product Liability
  • Technical-Selection Claims
  • Long-Lead Inventory

Reviewed by David Gleason, Principal — October 11, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability
Business Owners Policy / Commercial PackageLiability and property components evaluated together

What it is

A Business Owners Policy commonly combines liability and property coverages for eligible businesses. A Commercial Package Policy may combine multiple commercial coverage parts depending on the account and carrier.

Why businesses like yours commonly carry it

Businesses with premises, contents, inventory or other property exposures may ask GIB to evaluate whether liability and property components can be packaged where appropriate.

Possible coverage gap

Eligibility, included coverages and package structure vary by carrier. Commercial Property may also be written separately rather than as part of a package.

Learn more about Business Owners Policy / Commercial Package

Commonly Added Based on Operations

Commercial AutoBusiness vehicles, drivers and physical damage

What it is

Commercial Auto may address liability arising from covered business vehicles and, when selected, physical damage and other vehicle-related coverages.

Why businesses like yours commonly carry it

Businesses that own or regularly use vehicles may need a policy structured around business use, drivers and vehicle schedules.

Possible coverage gap

Personal auto policies may restrict or exclude business use, and General Liability is generally not a substitute for auto liability.

Learn more about Commercial Auto
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Suppliers invoice contractors constantly and are among the businesses most often impersonated in payment-change fraud.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for suppliers and distributors

Exposure-Dependent Coverages

Equipment BreakdownMechanical, electrical and pressure-system breakdown

What it is

Equipment Breakdown may address certain sudden mechanical, electrical or pressure-system breakdown losses, subject to the policy.

Why businesses like yours commonly carry it

Businesses dependent on refrigeration, production, HVAC, electrical or other critical equipment commonly consider it.

Possible coverage gap

Standard property forms may not address every internal mechanical or electrical breakdown.

Learn more about Equipment Breakdown
Commercial Crime / FidelityEmployee theft and certain fraud losses

What it is

Commercial Crime may address certain covered theft, fraud and funds-transfer losses, depending on the selected insuring agreements.

Why businesses like yours commonly carry it

Businesses handling money, inventory, payments or account access commonly consider crime coverage.

Possible coverage gap

Property and cyber policies do not necessarily cover every employee theft or social-engineering loss.

Learn more about Commercial Crime / Fidelity
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

High-Severity Products

A failed pump or valve can cause flooding, process interruption or public-infrastructure claims. Water damage from a failed product is one of the more severe supplier claims, a pattern covered in product liability for construction material suppliers.

A failed pump or valve can cause flooding, process interruption or public-infrastructure claims

Technical Selection

Sizing and application advice can create service allegations.

Sizing and application advice can create service allegations

Long-Lead Inventory

Large pumps and controls can be expensive and difficult to replace quickly.

Large pumps and controls can be expensive and difficult to replace quickly

Delivery

Pipe and pumps can require specialized hauling.

Pipe and pumps can require specialized hauling

Middle-Market Account Profile

A larger pump/waterworks supplier should identify municipal versus private revenue, high-value pumps, controls, valves, pipe, fabrication, testing, technical selection, field startup, long-lead equipment and specialized delivery or crane needs.

high-value pumps
controls
valves
pipe
fabrication
testing
technical selection
field startup

Coverage Priorities for This Niche

Products liability and excess reflect the downstream severity of pump/valve failure, while property/cargo protect expensive equipment before delivery. If staff performs engineering-like selection, startup or controls integration, E&O exposure should be reviewed. Fleet, WC and cyber complete the operating program.

Products liability and excess reflect the downstream severity of pump/valve failure, while property/cargo protect expensive equipment before delivery
If staff performs engineering-like selection, startup or controls integration, E&O exposure should be reviewed
Fleet, WC and cyber complete the operating program

Underwriting Questions Before Marketing the Account

Questions worth reviewing before marketing or binding this account:

What percentage of revenue is municipal/public works?
Does staff size or select pumps for applications?
Is startup/commissioning performed onsite?
What is the maximum value of one custom pump shipment?
Are controls or automation integrated by the supplier?

Coverage Gaps Worth Checking

A pump or valve failure can affect an entire commercial building, municipal system or industrial process. The products and excess program should reflect that severity. If the supplier performs startup, commissioning, controls integration or application engineering, professional liability should be considered in addition to GL.

A pump or valve failure can affect an entire commercial building, municipal system or industrial process
The products and excess program should reflect that severity
If the supplier performs startup, commissioning, controls integration or application engineering, professional liability should be considered in addition to GL

What a Strong Submission Looks Like

Break out municipal, industrial and contractor sales; identify custom pumps and controls; show maximum shipment value, technical staff, startup services, delivery methods, top manufacturers and claims. Public-works contract requirements and manufacturer indemnity should be included for larger accounts.

Public-works contract requirements and manufacturer indemnity should be included for larger accounts

Municipal and Infrastructure Contracts Increase Complexity

Suppliers serving public works can face submittal requirements, warranties, liquidated-damage pressure and long replacement lead times for custom pumps or controls. The broker should understand where the company's responsibility ends: simple distribution, application engineering, startup, commissioning or ongoing service. Those distinctions affect GL, professional liability, cargo, auto and excess. For large municipal orders, offsite storage and project-specific transit values should also be confirmed.

The broker should understand where the company's responsibility ends: simple distribution, application engineering, startup, commissioning or ongoing service
Those distinctions affect GL, professional liability, cargo, auto and excess
For large municipal orders, offsite storage and project-specific transit values should also be confirmed

Frequently asked questions

8 questions — start typing to filter

Is pump failure a products claim?

It can be — a pump that fails and causes flooding, contamination or a service interruption can be blamed on a defect in the supplied unit, creating a products liability claim.

Does sizing advice create professional exposure?

Potentially — recommending pump sizing or system specifications for a municipal or commercial application takes on a professional-advice element beyond simple distribution.

Are municipal projects higher risk?

They can be — municipal waterworks projects often carry higher contract-required limits and more severe consequences if a supplied component fails in public infrastructure.

Does cargo coverage apply to pumps and valves in transit?

Yes — pumps and waterworks components can be high-value per shipment, so cargo limits should reflect real delivery values.

Does equipment breakdown apply to inventory?

Generally it protects operating machinery rather than simply stock.

Should waterworks suppliers consider high excess limits?

Potentially — a failure tied to municipal or commercial water infrastructure can generate damages well beyond a standard underlying limit, especially on public-agency contracts.

Does emergency/standby pump work carry different exposure?

Yes — a standby or emergency pump system's failure during an actual emergency (a flood event, a fire-suppression demand) tends to produce more severe consequences than a routine operational failure.

Does supplying a control panel or SCADA integration with a pump change the coverage question?

It usually broadens it. A pump on its own is a product; a packaged system with a control panel, instrumentation and programming is a product plus a configuration someone performed, and the two can fail in different ways. If a station floods because the programming logic missed a condition, the allegation is generally about the work rather than about a defective part, which is professional or technology territory rather than ordinary products liability. The remote access side brings a cyber dimension as well, particularly on municipal systems. Suppliers that assemble and program panels commonly describe that work separately on the application, since a products-only form may not have been written around it.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 11, 2026