Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

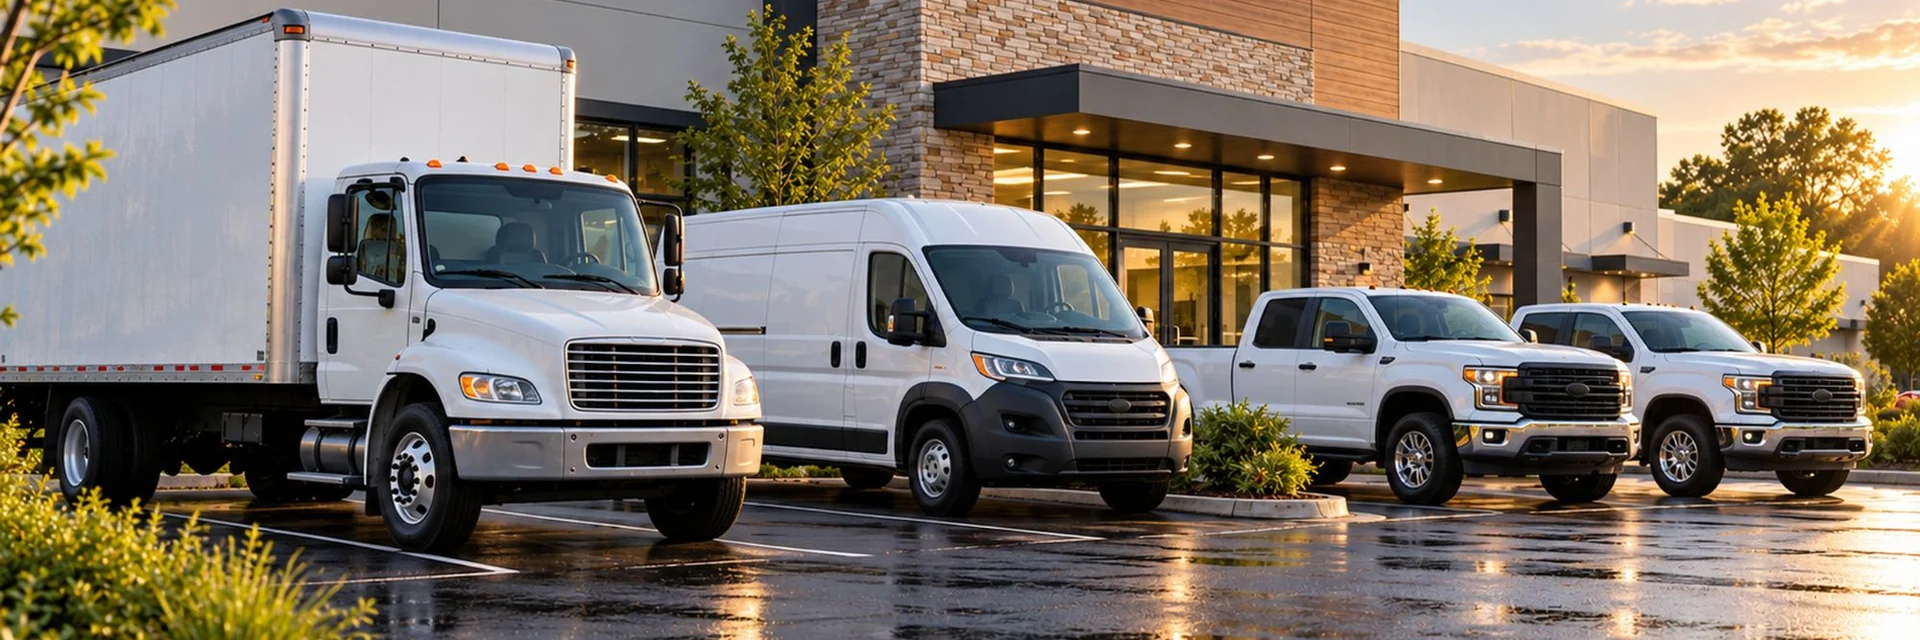
A mixed commercial fleet parked on wet asphalt outside a commercial building at sunrise — a box truck, a cargo van and two crew-cab pickups — commercial auto insurance for California businesses

Trucks, vans and fleets

Commercial Auto Insurance California

844-97-USAVE

A vehicle used for business is rarely covered the way its owner assumes. Personal auto policies generally exclude business use, and the gap tends to be discovered after an accident rather than before one — by a restaurant running deliveries, a clinic moving samples, or an office whose staff run errands in their own cars.

  • Owned & Hired Vehicles
  • Driver Records
  • Physical Damage

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Modern businesses commonly rely on email, banking, accounting systems, websites, cloud services and electronic records.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about small business cyber insurance in California

Exposure-Dependent Coverages

Business Owners Policy / Commercial PackageLiability and property components evaluated together

What it is

A Business Owners Policy commonly combines liability and property coverages for eligible businesses. A Commercial Package Policy may combine multiple commercial coverage parts depending on the account and carrier.

Why businesses like yours commonly carry it

Businesses with premises, contents, inventory or other property exposures may ask GIB to evaluate whether liability and property components can be packaged where appropriate.

Possible coverage gap

Eligibility, included coverages and package structure vary by carrier. Commercial Property may also be written separately rather than as part of a package.

Learn more about Business Owners Policy / Commercial Package
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What California business owners say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

When a business needs commercial auto rather than personal

The test is use, not ownership or appearance.

Read more

A vehicle titled to the business generally needs a commercial policy. So does a personal vehicle used regularly enough for business that a personal carrier would call it a business use, and a vehicle carrying goods, equipment or passengers for the operation.

The gray area that causes most trouble is the owner’s own car, used for both. Many personal policies will respond to incidental use and exclude regular business use, and the line between those is decided by the carrier after a claim. Describing the actual pattern of use at the start is far cheaper than arguing it later.

Vehicles titled to the business
Personal vehicles used regularly for business errands or deliveries
Anything carrying goods, equipment or passengers for the operation
Employee vehicles used for work, which raises non-owned exposure

Hired and non-owned, the cover most businesses forget

A business can be liable for an accident in a vehicle it neither owns nor insures.

Read more

An employee running a bank deposit in their own car, a rented van for an event, a staff member collecting supplies — all of it can reach the business, and the employee’s personal policy is not usually enough to answer for it.

Hired and non-owned auto liability is often a modest addition to a program and is one of the more common genuine gaps we find on an otherwise well-built account. It is liability cover, not physical damage, so it answers for harm to others rather than for the vehicle itself.

Covers the business for vehicles it does not own or insure
An employee running a work errand in their own car is the common case
Liability only -- it does not cover damage to the vehicle itself

What drives the price

Underwriters generally look at the vehicles, the drivers and the radius.

Read more

Vehicle type and value, how far and how often they travel, what they carry, and the driving records of the people behind the wheel all feed the rate. Loss history matters, and so does whether the business can show it checks motor vehicle records and has a written driver standard.

For a small fleet, the single most effective thing a business can do before renewal is clean up its driver list — remove people who have left, add those who have not been disclosed, and be able to show the records are pulled. An undisclosed driver found after a loss is a problem that is entirely avoidable.

Vehicle type, value and what it carries
Radius of operation and annual mileage
Driver records, and whether the business checks them
Prior losses, and any gap in prior coverage

Physical damage, and what a lender or lessor will require

Liability answers for what you do to others; comprehensive and collision answer for your own vehicle, and they are optional unless something else requires them.

Read more

A lender or a lessor almost always does, and will usually want to be named as a loss payee so a claim payment reaches them.

Where a vehicle is older, the question is whether the premium and deductible are worth the actual cash value likely to be paid. That is a straightforward calculation and worth doing deliberately rather than carrying the cover out of habit.

Comprehensive and collision are optional unless a lender or lessor requires them
A lender will usually want to be named as loss payee
On an older vehicle, weigh premium and deductible against actual cash value

What tends to raise the bar

Where higher limits and extra endorsements are commonly requested

Patterns this agency typically sees, not a statement of what any particular customer, landlord, agency or carrier will ask for.

Customer agreements around two million dollars and up

Larger accounts are where umbrella or excess limits start being written into the insurance exhibit, and where a designated-location aggregate is most often asked for. The figure is a rough threshold we tend to see rather than a rule — plenty of smaller agreements ask for more, and some larger ones ask for less.

Landlords and property management companies

The manager, the building owner and sometimes a lender are commonly all named, and the waiver of subrogation is often mutual. A management company typically has one standard insurance exhibit it applies to every tenant and every vendor, and the lease usually carries it rather than a separate document.

Retail centers, malls and mixed-use buildings

Center rules commonly set named additional insureds and specific limits before anyone is cleared to trade or to work on site, and the requirement frequently comes from the center itself or its property manager rather than from the party you signed with.

High-rise and multi-tenant premises

Height, occupancy and water damage exposure commonly push limits up and bring specific endorsements with them. Building access rules for your own staff and for anyone you send in are frequently a separate document again.

Colleges, universities and school districts

Institutional purchase terms commonly specify limits and endorsements directly, and depending on the work may ask about lines a general liability policy does not carry as standard — professional liability, crime or a fidelity bond among them.

Hospitals and health systems

Vendor credentialing commonly layers its own insurance conditions on top of the contract, checked by a third-party service rather than by the people who hired you, and the conditions frequently differ between facilities inside one system.

Vendor onboarding and compliance portals

Larger customers increasingly hand certificate review to an automated compliance service. It reads the certificate against the agreement and rejects on wording, so a policy that genuinely answers the requirement is commonly turned away over how the endorsement is described rather than over what it does.

Cities, counties and state agencies as customers

A public buyer writes its own wording into the purchase order, and it is rarely identical to what a standard commercial policy already provides. Evidence is usually due on a deadline tied to the award rather than to the start of work.

Licensing boards and regulators

Some professions and some permits carry a minimum limit set by the regulator, entirely separate from anything a customer asks for. It is worth reading that condition as its own document rather than assuming a client contract covers it.

What tends to be asked for alongside the higher limits

Designated-location aggregateCG 25 04
The one that surprises people most. A general aggregate is normally shared across everything running in the policy term, so a claim at one site or on one account can erode the limit the next agreement assumed was there. This sets a separate limit for each designated location instead.
Additional insured — managers or lessors of premisesCG 20 11
The form a landlord or property manager is usually asking for. It reaches their interest in the premises you occupy, which is a narrower thing than being named generally.
Additional insured — designated person or organizationCG 20 26
The broader one a customer, a franchisor or an institution commonly names. Scheduled and blanket versions both exist, and larger agreements often specify which.
Primary and non-contributoryoften CG 20 01
Decides whether your policy responds first or shares with the other party’s own cover. Usually keyed to a written agreement requiring it.
Waiver of subrogationCG 24 04
Gives up the insurer’s right to recover from the other party after paying a claim. Frequently named alongside additional insured status rather than instead of it, and a separate waiver is commonly asked for on the workers compensation policy.
Higher umbrella or excess limits
Commonly the first thing an insurance exhibit raises. If the underlying limits do not match what the umbrella sits above, the tower may not respond the way the agreement assumes.

Two real examples, published by the buyers themselves

Reading an actual insurance clause is worth more than any summary of one. Both of these are public, and they ask for different things — which is the point.

  • City of San Diego — insurance and bonds for vendorsApplies to vendors and services regardless of the dollar amount of the work, with evidence due within ten days of provisional award rather than before work starts. Asks for the CGL on an ISO occurrence form, for primary and non-contributory wording, for additional insured status shown on a separate endorsement page rather than on the certificate, and for a waiver of subrogation on the workers compensation policy.
  • University of California, Irvine — supplier insurance requirementsA purchasing department rather than a permit counter, and the list runs past general liability: professional liability and a fidelity bond or crime coverage both appear, workers compensation turns on whether the supplier has employees at all, and the certificate holder wording is specified down to the mailing address. The page calls its own figures guidelines "subject to change, based upon the specific transaction".

Commercial auto across California’s metro areas

Where vehicles are garaged and where they actually run are both rating questions, and in California they often differ by a long way.

Read more

Los Angeles and Orange County combine the heaviest traffic density in the state with its highest claim severity, and a vehicle garaged there generally prices differently from the same vehicle in a rural county. The Inland Empire’s logistics corridor puts large numbers of commercial vehicles on the same few interstates, which concentrates both frequency and the chance of a multi-vehicle loss.

The Bay Area adds dense urban delivery, limited parking and a high incidence of vehicle theft and break-ins in some areas. The Central Valley along the 99 and the 5 is long-haul and agricultural movement, where the miles are higher and the speeds are greater even if the traffic is lighter. A business running vehicles across several of these is usually better served by describing the real routes than by listing one garaging address and hoping the rating follows.

Los Angeles and Orange County: highest density and highest claim severity
Inland Empire: concentrated commercial traffic on a few corridors
Bay Area: dense urban delivery, parking and theft exposure
Central Valley: longer distances and higher speeds on the 5 and the 99
Garaging address and actual route are two different rating facts

Who is covered to drive, and why the policy symbols decide it

A commercial auto policy does not simply say "our vehicles".

Read more

It uses numbered symbols on the declarations page to describe which categories of vehicle each coverage applies to: owned vehicles, hired vehicles, non-owned vehicles, specifically scheduled vehicles, or any auto. Those symbols are the actual scope of the policy, and two otherwise identical policies with different symbols are not the same cover.

This is where the most expensive surprises happen, because the symbols decide whether a vehicle nobody remembered to add is covered at all. A newly purchased truck, a van borrowed from another business, a rented vehicle during a busy week, an employee’s own car used for a delivery — each of those is a different symbol question. Reading the declarations page once, and knowing which symbols you bought, is worth more than reading the whole policy.

Symbols on the declarations page define which vehicles each coverage applies to
Owned, hired, non-owned and scheduled are different categories
A newly acquired vehicle may have limited automatic coverage, with a deadline
Borrowed and rented vehicles are not automatically treated the same way

The first hour after an accident

What gets recorded at the scene tends to decide how a commercial auto claim runs, far more than anything argued later.

Read more

Photographs of all vehicles and the wider scene, the other driver’s details and insurer, any police report number, and the names of anyone who saw it are the whole list. Businesses that keep a short written card in each vehicle generally get better files than those relying on a shaken driver to remember a process.

Reporting promptly matters for the same reason it matters in workers compensation: the facts are available now and will not be later. It is also worth telling drivers in advance not to discuss fault at the scene. That is not about avoiding responsibility; it is that the person who was just in a collision is rarely in a position to assess what caused it, and their account may be relied on afterwards.

Photographs of every vehicle and the wider scene, not just the damage
Other driver, insurer, plate and any police report number
Witness names and contact details, collected at the time
Report to the carrier promptly rather than after an internal review
Drivers should exchange information without assessing fault

Rented, leased and employee-owned vehicles

Most businesses eventually use a vehicle they do not own, and each version raises a different question.

Read more

A rental taken for a few days is usually a hired auto question, and whether physical damage to that rental is covered depends on what was bought rather than being automatic. A leased vehicle typically brings the lessor’s own requirements, commonly including physical damage at agreed limits and the lessor named on the policy.

An employee driving their own car on business is the one most often missed. Their personal policy generally responds first, but it may exclude business use, and if it does not respond fully the claim can reach the business. Non-owned auto liability is the coverage aimed at that gap. It is usually inexpensive relative to the exposure, and the businesses that need it most are often the ones who believe they have no vehicle exposure at all.

Hired auto: liability and physical damage are separate decisions
Leased vehicles: the lessor usually sets its own requirements
Employee-owned cars on business errands: non-owned auto liability
A business with no vehicles can still have a vehicle exposure

Frequently asked questions

15 questions — start typing to filter

Will my personal auto policy cover me if I am working?

Often not. Personal policies commonly respond to incidental use and exclude regular business use, and where the line sits is decided by the carrier after a claim rather than before one. If a vehicle is used for deliveries, for carrying equipment, or regularly for work errands, that should be described rather than assumed to be covered.

What is hired and non-owned auto coverage?

It covers the business’s liability arising from vehicles it does not own — a rented van, or an employee’s own car used for work. It is liability cover rather than physical damage, so it answers for harm to others and not for the vehicle itself. It is one of the more common genuine gaps on an otherwise well-built program.

Does commercial auto cover my employee’s commute?

Ordinary commuting is generally treated as personal use rather than business use, though the detail varies by policy and by how the vehicle is scheduled. Where an employee runs a work errand on the way in or home, that is where the line gets tested, which is a reason to carry hired and non-owned cover.

How many vehicles make a fleet?

There is no single threshold, and carriers differ. What usually changes with size is how the account is rated and whether fleet-level controls — a written driver policy, regular record checks, telematics — start earning credit. A business with a handful of vehicles is often better served being rated as a small fleet than as individual units.

Do I need to list every driver?

You need to disclose the drivers the carrier asks about, and keeping that list current matters more than most businesses expect. An undisclosed driver found after a loss creates a problem that was entirely avoidable, and a list carrying people who left simply costs money.

Is cargo covered by commercial auto?

Generally not. Commercial auto covers liability and, where purchased, damage to the vehicle. Goods being carried are usually covered under a motor truck cargo or inland marine policy instead, which is a separate purchase and worth raising if the business moves anything of value.

What limits do businesses usually carry?

Contracts and leases frequently set a floor, and many businesses then sit at that floor without asking whether it suits them. Because auto claims can reach well past a primary limit, an umbrella sitting over the auto policy is often a more efficient way to buy height than raising the primary limit alone.

Can a vehicle be insured under a business owners policy?

No. A BOP packages property and general liability; vehicles need a commercial auto policy, and the two are written separately even where the same carrier issues both. A business that has a BOP and assumes its van is included has a gap rather than a policy.

What are commercial auto symbols and why do they matter?

They are the numbered codes on the declarations page that say which categories of vehicle each coverage applies to — owned, hired, non-owned, scheduled, or any auto. They are the real scope of the policy. Two policies with the same limits and different symbols cover different things, and most unpleasant surprises in this line trace back to a symbol nobody read.

Does commercial auto cover a rental car on a business trip?

It can, through hired auto coverage, but liability and physical damage are separate decisions and a policy may include one without the other. If physical damage on hired autos was not purchased, the rental company’s damage waiver may be the only thing standing behind the vehicle itself. Worth confirming before a trip rather than at the counter.

What is uninsured and underinsured motorist coverage?

It responds when the other driver is at fault and has no insurance, or not enough of it. Given how many drivers carry only minimum limits, it is one of the more practically useful coverages on a commercial auto policy rather than a formality. Rules on how it can be offered and rejected are set by California, so the offer you receive is not arbitrary.

Do I need a DOT number to run commercial vehicles in California?

It depends on vehicle weight, what is being carried, and whether operations cross state lines — and both federal and California rules apply. This is a question for the CHP and the FMCSA rather than for an insurance answer, but it matters here too: carriers generally ask, and the answer affects both appetite and the filings a policy may need to support.

Who pays when an employee crashes their own car on a work errand?

Their personal policy generally responds first, but personal policies commonly limit or exclude business use, and when the personal limits are exhausted or do not apply the claim can reach the business. Non-owned auto liability is built for exactly that situation and is usually modest in cost compared with the exposure it addresses.

Does a dashcam or telematics program change anything?

Often yes, in two ways. Some carriers price favorably for verified telematics or recognize a documented program, and separately the footage frequently resolves disputed-fault claims quickly, which is worth real money regardless of any discount. The practical caution is to decide in advance how footage is retained, because a program with no retention policy helps nobody.

What happens to the premium after an at-fault accident?

It commonly rises, though by how much depends on the size of the loss, the rest of the loss history and the size of the fleet. One claim on a well-documented fleet with a driver program reads differently from the same claim on a fleet with no records. The useful work is done before the claim: driver files, motor vehicle record checks and a written policy are what give a carrier a reason to stay.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 12, 2026