Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

A loaded dump truck on a job site — dirt, sand and gravel hauling insurance

California commercial insurance

Dirt, Sand & Gravel Hauling Insurance California

844-97-USAVE

Aggregate hauling — dirt, sand, gravel, base rock and similar bulk material — carries the same commercial auto and motor carrier compliance as any dump truck operation, plus material-specific exposure: tailgate spillage, overweight loads, and pit or quarry loading operations that a standard trucking policy doesn't always price correctly.

  • Commercial Auto Liability
  • Cargo Coverage
  • Overweight & Spillage Exposure

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability
Commercial AutoBusiness vehicles, drivers and physical damage

What it is

Commercial Auto may address liability arising from covered business vehicles and, when selected, physical damage and other vehicle-related coverages.

Why businesses like yours commonly carry it

Businesses that own or regularly use vehicles may need a policy structured around business use, drivers and vehicle schedules.

Possible coverage gap

Personal auto policies may restrict or exclude business use, and General Liability is generally not a substitute for auto liability.

Learn more about Commercial Auto

Commonly Added Based on Operations

Motor Truck CargoCustomers' freight while in transit

What it is

Motor Truck Cargo may address covered loss or damage to property transported for others, subject to commodities, limits and exclusions.

Why businesses like yours commonly carry it

Motor carriers may be contractually responsible for customers' cargo while it is in their care, custody or control.

Possible coverage gap

Commercial Auto liability does not automatically insure customers' cargo against physical loss.

Learn more about Motor Truck Cargo
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Motor carriers increasingly rely on dispatch, ELD, telematics, payment, customer and driver systems.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for trucking companies

Exposure-Dependent Coverages

Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What trucking and transportation businesses say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

How aggregate hauling differs from general trucking

Dirt, sand and gravel haulers typically run loaded in one direction and empty in the other, on a repeated short-haul cycle between a pit, quarry or jobsite and a delivery point — that repetition concentrates exposure into loading, unloading and tailgate operations more than long-haul freight does.

Material density varies significantly — wet sand, base rock and loose dirt all load to different actual weights per cubic yard — which is part of why overweight citations are a real, recurring exposure in this trade, not an edge case.

Short-haul, repeated loading/unloading cycle is the core exposure pattern
Material density affects actual load weight, not just volume
Overweight citations are a recurring, not edge-case, exposure
Pit and quarry loading sites add their own access and traffic risk

Commercial auto and cargo coverage for hauling operations

Physical damage coverage for the truck, liability sized to a fully loaded vehicle, and cargo coverage that reflects the actual material hauled — aggregate, sand, base rock, demolition spoils — form the baseline for a dirt, sand and gravel hauling program.

Owner-operators hauling under someone else's authority need to confirm whose policy actually responds — the trucking company's non-trucking/bobtail coverage typically doesn't cover the truck while it's under dispatch, and assuming otherwise is a common gap.

Physical damage and liability should reflect a fully loaded truck
Cargo coverage should match the actual material hauled
Owner-operators: confirm whose policy responds while under dispatch
Non-trucking/bobtail coverage has real gaps — don't assume it's continuous
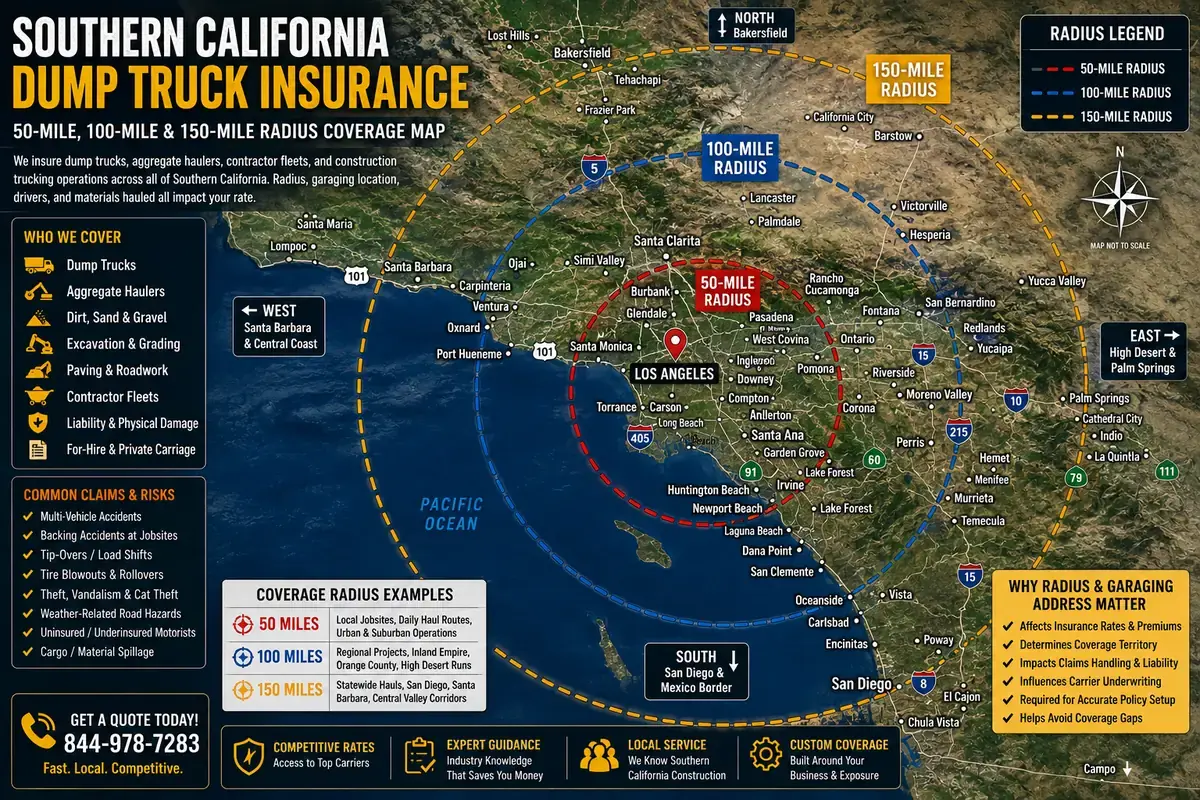
Southern California dump truck and material hauler insurance coverage radius map — 50, 100 and 150-mile operating zones from Gleason Insurance Brokers

One Stop · We Shop · Real Results

844-978-7283
  • Dump trucks
  • Aggregate haulers
  • Dirt, sand and gravel
  • Excavation and grading
  • Paving and roadwork
  • Contractor fleets
  • Liability and physical damage
  • For-hire and private carriage
  • Multi-vehicle accidents
  • Backing accidents at jobsites
  • Tip-overs and load shifts
  • Tire blowouts and rollovers
  • Theft, vandalism and catalytic converter theft
  • Weather-related road hazards
  • Uninsured and underinsured motorists
  • Cargo and material spillage
  • Affects rates and premiums
  • Determines coverage territory
  • Impacts claims handling and liability
  • Influences carrier underwriting
  • Required for accurate policy setup

50 miles — Local jobsites, daily haul routes, urban and suburban operations

100 miles — Regional projects, Inland Empire, Orange County, High Desert runs

150 miles — Statewide hauls, San Diego, Santa Barbara, Central Valley corridors

Radius, garaging location, drivers and the materials hauled can all influence commercial insurance pricing and underwriting eligibility. The zones shown describe how far this agency places coverage; they are not a statement of what any policy covers.

Overweight loads, spillage and tailgate exposure

A dropped or improperly latched tailgate, a load that shifts on a grade, or material striking a following vehicle are among the most common claims in this trade — confirm this specific exposure is explicitly addressed in the policy rather than assumed bundled into standard auto liability.

An overloaded truck involved in an accident can complicate a claim regardless of fault, since it raises compliance questions that go beyond the accident itself — accurate weigh tickets and load documentation matter as much for insurance as for DOT compliance.

Tailgate and spillage incidents are among the most common claims
Confirm this exposure is explicitly covered, not assumed
Overweight loads can complicate a claim beyond simple fault
Weigh tickets and load documentation support both compliance and claims

USDOT, CA number and Motor Carrier Permit requirements

Aggregate hauling triggers the same federal and state motor carrier registrations as any dump truck operation — a USDOT number, a California CA number and a California Motor Carrier Permit are separate registrations, and applicability depends on gross vehicle weight and the specific operation, not the material hauled.

The MC 65 M Certificate of Insurance is the specific filing California DMV uses for MCP financial-responsibility — it's typically filed by the insurer, not the contractor, and timing should be planned for rather than assumed immediate.

USDOT, CA number and MCP are three separate registrations
Applicability depends on GVW and operation, not the material hauled
MC 65 M is filed by the insurer for MCP financial responsibility
Plan ahead for new or reinstated MCP processing time

Driver qualification for aggregate hauling

Written driver criteria — minimum experience, MVR standards, limits on major violations — matter given the vehicle weight and the repeated loading-site maneuvering this work involves, often on unpaved or uneven pit and quarry surfaces.

Report new drivers to the carrier before they start hauling, not after — several carriers in this space require driver approval, and waiting creates a coverage question at the worst possible time.

Written driver criteria should reflect this trade's specific exposure
Pit and quarry site maneuvering adds real jobsite risk
Report new drivers before they start hauling
Confirm whether your carrier requires driver approval

Getting hauling coverage and compliance aligned

Confirm which of USDOT, CA number and MCP apply to your specific hauling operation, and coordinate commercial auto, cargo, driver qualification and any required DMV filings together rather than piecemeal.

Gleason Insurance Brokers places commercial auto and cargo coverage for dirt, sand and gravel hauling operations across California — call 844-978-7283 or request a quote with your vehicle, material and operation detail.

Confirm USDOT/CA number/MCP applicability for your operation
Coordinate auto, cargo, driver qualification and DMV filings together
We handle MC 65 M filing coordination as part of the program
Call 844-978-7283 or request a quote to get started

Frequently asked questions

9 questions — start typing to filter

Is dirt, sand and gravel hauling insurance different from dump truck insurance?

They're closely related, not different products. Both need the same commercial auto liability, physical damage and USDOT/CA number/MCP compliance — this page focuses specifically on the cargo, weight and material exposure of aggregate hauling, while our dump truck insurance page covers the vehicle side more broadly.

Do I need a USDOT number for aggregate hauling?

Possibly — USDOT requirements depend on vehicle weight, interstate operations and other federal factors, not the material hauled specifically. Verify applicability with FMCSA.

Do I need a California Motor Carrier Permit for hauling dirt or sand?

Possibly — California's MCP requirements depend on the vehicle and operation. Verify current requirements through California DMV Motor Carrier Services.

I'm an owner-operator hauling for a general contractor — whose insurance covers me?

It depends on the arrangement. If you're hauling under someone else's motor carrier authority and dispatch, their policy may respond while under dispatch, but your own non-trucking/bobtail coverage typically has gaps outside of that. Confirm the specifics in writing rather than assuming continuous coverage.

Does the type of material I haul affect my insurance cost?

It can. Material density affects actual load weight, and some materials carry more spillage or overweight exposure than others. Give your broker the real material mix rather than a generic "dirt and gravel" description.

What if I load at a quarry or pit, not a construction site?

That's a normal part of this trade and should be described accurately in your application — pit and quarry loading sites have their own access, traffic and maneuvering exposure that's useful for an underwriter to see up front.

Do I need cargo insurance in addition to commercial auto liability?

Typically yes, for the material's value and any liability tied to it in transit — confirm cargo coverage is included and reflects the actual material hauled, not assumed as part of standard auto liability.

Is business auto insurance the same as commercial auto insurance for a hauling truck?

Yes — business auto insurance and commercial auto insurance are the same coverage, just different common names for a policy covering vehicles used for business rather than personal use.

If I stop hauling and cancel the policy, am I still responsible for premium?

Often yes, for a notice period. Where the policy carries the MC 65 M filing behind a Motor Carrier Permit, that filing comes off on the DMV's timetable rather than on the cancellation date, and premium can stay due in the meantime. There is a second version of this question for owner-operators: if you have been hauling aggregate under someone else's authority, their filing is not yours to cancel, and your own non-trucking coverage may be the only thing left responding once dispatch ends. Confirm which policy carries which filing before anything is canceled.

Additional official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 12, 2026