Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

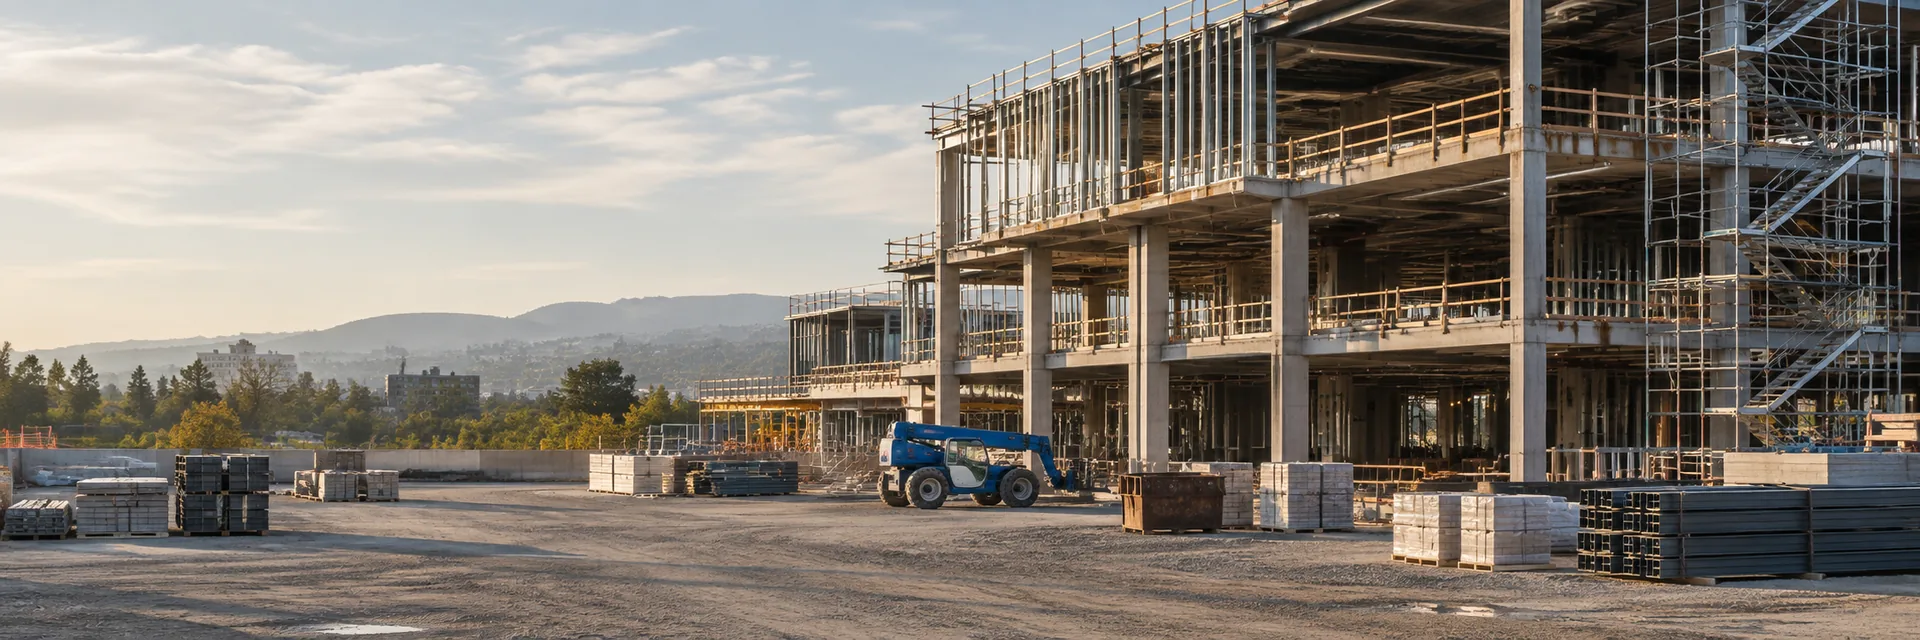
A commercial building under construction with a tower crane overhead — general contractor insurance package — GL, workers comp and equipment

California commercial insurance

General Contractor Insurance Package CA

844-97-USAVE

General contractors carry more moving parts than almost any other classification — their own liability, subcontractor risk transfer, multiple projects at once, and whatever a specific owner or lender contract layers on top. A package built around that reality beats stitching individual policies together after the fact.

  • Coordinated Package
  • Subcontractor Risk Transfer
  • Owner & Lender Requirements

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Contractor Equipment / Inland MarineMobile tools, equipment and property away from premises

What it is

Inland Marine is commonly used for tools, equipment and certain mobile property that moves between locations or jobsites.

Why businesses like yours commonly carry it

Contractors frequently move tools, testing equipment and mobile machinery among jobsites.

Possible coverage gap

General Liability should not be assumed to insure the business's own tools and equipment against theft or physical damage.

Learn more about Contractor Equipment / Inland Marine
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Contractors commonly use email, electronic banking, project platforms, payroll systems and cloud document storage.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for contractors

Exposure-Dependent Coverages

Installation FloaterMaterials awaiting or undergoing installation

What it is

An Installation Floater may cover certain materials and equipment in transit, temporary storage and during installation, subject to the policy.

Why businesses like yours commonly carry it

Businesses responsible for materials before final installation commonly consider this coverage.

Possible coverage gap

A basic liability policy generally should not be assumed to cover the insured's materials against physical loss before installation is complete.

Learn more about Installation Floater
Builder's RiskProject property during construction

What it is

Builder's Risk may insure covered buildings, materials and certain project property while construction is underway.

Why businesses like yours commonly carry it

Owners, developers and contractors commonly consider it when a structure or major renovation is exposed during construction.

Possible coverage gap

Commercial Property and General Liability are not automatic substitutes for course-of-construction property coverage.

Learn more about Builder's Risk
Contractors Pollution LiabilityPollution conditions and cleanup liability

What it is

Pollution Liability may address covered cleanup costs and third-party injury or property damage arising from pollution conditions.

Why businesses like yours commonly carry it

Businesses working with fuels, chemicals, soil, water, demolition or environmental conditions may have pollution exposures.

Possible coverage gap

Standard General Liability commonly contains pollution exclusions or limitations.

Learn more about Contractors Pollution Liability
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Why GCs need a coordinated package, not separate policies

A general contractor's risk includes their own work, their subcontractors' work performed under their license and contracts, and the coordination risk of managing multiple trades on one jobsite at once.

Read more

General liability, workers compensation, commercial auto, umbrella and a CSLB bond typically all need to work together rather than being purchased and renewed separately.

Effective dates, named insureds and classification consistency across policies matter more for GCs than almost any other trade — a gap between what the GL policy assumes and what the auto or umbrella policy assumes is exactly where a claim can fall through.

Construction businesses also handle large, recurring payments and coordinate with dozens of vendors and subs — exactly the profile that makes cyber liability worth a real look, not just a line item to skip.

Own-work liability plus subcontractor risk transfer, together
GL, workers comp, auto and umbrella coordinated as one program, with bonding handled by the same agency
Effective dates and named insureds should align across policies
Multiple simultaneous projects add coordination risk beyond any single job
San Francisco's Mandatory Seismic Retrofit Program is a real, ongoing source of occupied-building renovation work — see the San Francisco/Oakland metro page for the program specifics

Subcontractor risk transfer is a GC's biggest lever

A formal process for verifying subcontractor insurance — the actual certificate, the required endorsements, and current expiration dates, not just a yes/no confirmation — is the single highest-leverage habit a general contractor can build.

Read more

Uninsured or under-endorsed subcontractors can shift real exposure back onto the GC's own policy.

Written subcontract agreements with indemnification language work alongside insurance requirements, not instead of them — the two are complementary risk-transfer tools, and a contract missing one or the other leaves a real gap.

Treat the above as what is commonly asked for, not as a guarantee. A carrier may require any of it as a subject-to or as a condition of the terms it issues, and the version that governs is the policy itself once bound. Because contract language is a legal question as much as an insurance one, seek legal counsel on your own agreements.

Verify subcontractor certificates and endorsements before work starts
Track expiration dates, not just a one-time confirmation
Written subcontracts with indemnification support the insurance side
Uninsured subcontractor exposure can flow back to the GC's own policy

How risk transfer actually flows

Project Owner or Developer → General Contractor → Subcontractor

Contract requirements flow down the chain. Uninsured risk flows back up it wherever a link is missed. Open a handoff to see what commonly travels with it.

Project Owner / Developer
  • Additional insured, ongoing operationsoften CG 20 10Extends the downstream party’s general liability to the upstream party for work still in progress. It is the form most contracts have in mind when they say "name us as additional insured", and on its own it generally stops responding once the work is finished.
  • Additional insured, completed operationsoften CG 20 37Covers the same party for claims arising after the work is complete — which is when a great many construction claims actually surface. A contract asking for both ongoing and completed operations is usually asking for two separate endorsements, not one.
  • Primary and non-contributoryoften CG 20 01Commonly decides whether the downstream policy responds first or shares with the upstream party’s own cover. Usually keyed to a written contract requiring it.
  • Waiver of subrogationCG 24 04Gives up the insurer’s right to recover from the upstream party after paying a claim. Frequently named alongside additional insured status rather than instead of it.
  • Indemnity in the prime contractThe contractual promise the insurance is meant to stand behind. California limits how far indemnity can reach on some construction contracts, so the wording matters as much as the endorsements attached to it.
  • Certificate, plus the endorsements behind itA certificate evidences that a policy existed on the day it was issued. It is not proof that any particular endorsement sits on that policy, which is why a requirement is commonly checked against the endorsement itself.

A wrap-up changes this picture. Where the owner or developer places an OCIP or CCIP, much of the enrolled work is covered under that program instead, and what each party still has to carry outside it is set by the wrap-up documents.

General Contractor
Subcontractor

The limits a contract asks for, and what each one means

Contracts commonly state required limits as well as required endorsements. One million dollars per occurrence with a two million dollar general aggregate is a combination many construction agreements use, but the figures vary by project, by owner and by trade, and the limit is only one number on the policy — it says nothing about what is excluded or which endorsements are attached.

Per occurrence
The most the policy generally pays for any one covered occurrence.
General aggregate
The most it generally pays across the policy term. Some contracts ask for it to apply per project, which is its own endorsement.
Products and completed operations aggregate
A separate bucket for claims arising after the work is finished, which is where completed-operations additional insured status becomes relevant.
Umbrella or excess above it
Sits above the underlying limits. If the underlying policy does not match what the umbrella requires beneath it, the tower may not respond as the contract assumes.

Meeting owner, lender and public agency requirements

Private commercial owners, developers, lenders and public agencies each tend to have their own insurance specifications — limits, additional insured wording, primary and noncontributory requirements, and sometimes a minimum AM Best carrier rating.

Read more

Reading the actual contract language before bidding avoids a scramble to fix a mismatch after award.

Public works adds DIR registration, prevailing wage and certified payroll on top of standard insurance requirements — a separate compliance layer that has its own lead time and shouldn't be assumed to already be handled.

A certificate holder and an additional insured are two different things a contract can ask for — see the real difference between them before assuming one satisfies the other. Licensing requirements, from the CSLB bond to workers comp exemptions, are summarized in our California contractor licensing compliance guide.

Owner, lender and agency requirements vary by contract
Read the actual insurance specification before bidding, not after award
Public works adds DIR, prevailing wage and certified payroll
Confirm any minimum carrier rating requirement explicitly

What tends to raise the bar

Where higher limits and extra endorsements are commonly requested

Patterns this agency typically sees, not a statement of what any particular project, agency or carrier will ask for.

Projects around two million dollars and up

Mid-sized and larger jobs are where umbrella or excess limits start being written into the insurance exhibit, and where a per-project aggregate is most often asked for. The figure is a rough threshold we tend to see rather than a rule — plenty of smaller contracts ask for more, and some larger ones ask for less.

Pulling a permit with a city or county

Some jurisdictions set their own insurance conditions before a permit is issued, separate from anything the project owner asks for. It is worth reading the permit conditions as its own document rather than assuming the contract covers it.

Encroachment permits and work in the public right of way

Working in a city, county or Caltrans right of way commonly carries its own limits, its own additional insured wording naming the agency, and sometimes a bond as well.

Public works

The awarding agency writes its requirements into the bid package, and they are rarely identical to what a standard commercial policy already provides. Bonding, DIR registration and certified payroll usually travel with them.

Property management companies and landlords

The manager, the building owner and sometimes a lender are commonly all named, and the waiver of subrogation is often mutual. A management company typically has one standard insurance exhibit it applies to every vendor.

Commercial retail, shopping centers and malls

Mall and shopping center rules commonly set named additional insureds and specific limits before anyone is cleared to work on site, and the requirement frequently comes from the center itself or its property management company rather than from the tenant who hired you.

High-rise buildings

Height, occupancy and water damage exposure commonly push limits up and bring specific endorsements with them. Building rules for contractor access are frequently a separate document again.

Colleges, universities and school districts

Institutional contract templates commonly specify limits and endorsements directly, and depending on the work may ask about coverages a construction policy does not carry as standard.

Caltrans and other government work

State and federal agencies commonly specify their own forms, their own wording and their own limits, and are usually the least flexible about substitutions.

What tends to be asked for alongside the higher limits

Per-project aggregateCG 25 03 or CG 25 04
The one that surprises people most. A general aggregate is normally shared across every job running in the policy term, so a claim on one project can erode the limit the next contract assumed was there. A per-project aggregate sets a limit for the designated project instead.
Additional insured, scheduled or blanketCG 20 10 and CG 20 37
Ongoing operations and completed operations are two separate endorsements, and larger contracts commonly ask for both.
Primary and non-contributoryoften CG 20 01
Decides whether the downstream policy responds first or shares with the upstream party’s own cover.
Waiver of subrogationCG 24 04
Frequently named alongside additional insured status rather than instead of it.
Higher umbrella or excess limits
Commonly the first thing an insurance exhibit raises. If the underlying limits do not match what the umbrella sits above, the tower may not respond the way the contract assumes.

Two real examples, published by the agencies themselves

Reading an actual insurance clause is worth more than any summary of one. Both of these are public, and they ask for different things — which is the point.

  • City of Los Angeles Bureau of Engineering — liability insurance for permitsStates a commercial minimum of $1 million with a $2 million aggregate, a thirty-day written cancellation notice, and the City named both as certificate holder AND as additional insured. It also expects proof to stay on file for as long as the encroachment exists, not just through construction.
  • Caltrans Encroachment Permits Manual — Chapter 200, section 203.3Asks for an endorsement naming the State of California, the Department and its directors, officers, employees and agents as additional named insureds — and for the certificate AND the endorsement to be furnished. A good illustration of why a certificate on its own is rarely what an agency means.

Coordinating coverage across multiple active projects

A GC running several projects at once needs to think about aggregate limits, not just per-project limits — a general liability policy's aggregate can be shared across all projects in a policy period unless a per-project aggregate endorsement is in place, which matters more as project count and size grow.

Read more

Bonding capacity works the same way — aggregate bonding capacity has to cover everything currently bonded, not just the newest project, which is why growing GCs benefit from tracking capacity proactively rather than discovering a constraint mid-bid.

Specialty fabrication trades — fabricated plate work and tank construction among them — carry their own equipment and product-liability profile that a generic GC package shouldn't just absorb without a direct look. Tools and smaller equipment are not covered by general liability; they go on a floater described on general contractor tools and equipment insurance.

Aggregate limits can be shared across simultaneous projects
A per-project aggregate endorsement addresses that specifically
Aggregate bonding capacity covers all active bonded work at once
Track capacity proactively as project count and size grow

A realistic scenario: coordinating coverage across a package

A GC running three residential remodels and one small commercial buildout at once has genuinely different exposure on each job — different subs, different material handling, different client relationships.

Read more

A package built as one bundled policy still needs each line reviewed against the specific mix of active work, not just renewed on autopilot from last year's schedule.

The value of a package over separately purchased lines isn't just administrative simplicity — it's that gaps between policies (a scope of work that falls between what GL and inland marine each assume the other covers) are far easier to catch when one broker is reviewing the whole picture against your actual active job list.

This is offered as a general, illustrative example of how this type of situation commonly plays out — not a specific case, and not a promise of how any real claim would be decided. For an actual situation, the specific policy language and a licensed attorney or the relevant regulatory authority are the right resources, not this page.

Active job mix should drive the annual package review, not just renewal
Separately purchased lines create more room for a gap between them
A package reviewed as a whole catches those gaps more reliably
Review timing should match when your typical project mix changes

Building the package with Gleason Insurance Brokers

We coordinate general liability, workers compensation, commercial auto and umbrella as one program for California general contractors, and handle the bonding alongside it through the same agency — not separate transactions that happen to renew around the same time.

Read more

Bonding stays its own agreement: a bond is a contract with a surety company, underwritten on your financials and your indemnity, and it does not package into a property and casualty program.

Share your current operations, active project list and any specific contract requirements, and we'll identify what's already well-structured and what needs attention. Call 844-978-7283 or request a quote to start.

One coordinated program, not separate disconnected policies
Built around your actual active project list
Reviewed against real contract and lender requirements
Call 844-978-7283 or request a quote to get started

Coordinating coverage for public works: new construction, renovation and highway work

A GC bidding across new construction, renovation and highway public works work needs a program flexible enough to reflect each project type's real differences, not one standard commercial package stretched across all three.

Read more

New construction public works generally follows the most familiar coverage pattern — builders risk, GL, bonding sized to contract value. Renovation of an occupied public facility adds real third-party liability exposure from the building's continued use during construction, and older public buildings can carry hazardous materials considerations worth confirming before bid.

Highway and Caltrans work is its own tier — higher umbrella/excess requirements, traffic-adjacent severity, and often its own encroachment permit and bonding requirements distinct from a standard vertical-construction public works job. A GC moving from typical city public works into a first Caltrans contract should confirm program limits reflect this before bidding, not discover a gap at bid review.

The project size, the trade mix of subcontractors involved, and the specific awarding jurisdiction all shape what a given public works contract actually requires — a GC managing several public works bids at once should confirm each project's requirements individually rather than applying one standard program across all of them. Send the insurance and bonding pages from the actual contract documents or bid proposal to your broker before bidding, not after the award.

New construction, renovation and highway public works each carry genuinely different coverage needs
Renovation of occupied public facilities adds real third-party liability and possible hazmat exposure
Highway/Caltrans work requires higher umbrella/excess limits and its own encroachment permit/bonding track
Confirm program limits before a first Caltrans bid, not after bid review flags a gap

New commercial construction: what changes from a standard trade package

New commercial construction — ground-up office, retail, industrial or mixed-use projects — carries coverage needs distinct from residential and renovation work: higher builders risk limits sized to the full project value, general liability limits that reflect the scale of a commercial structure's occupancy and use, and often a lender or project owner's own specific insurance requirements layered on top of standard coverage.

Read more

Confirm the actual project value and any owner/lender-required limits before assuming a standard commercial GC package fits a new ground-up project the same way it fits a smaller renovation.

New commercial construction also more often involves coordinating multiple subcontractor trades under one general liability and risk-transfer program, sometimes through an OCIP or CCIP wrap-up structure on larger projects — worth discussing directly if your new commercial construction volume is growing.

New commercial construction needs builders risk and GL limits sized to full project value and occupancy scale
Confirm any owner/lender-specific insurance requirements before assuming standard coverage fits
Larger new commercial construction projects often benefit from OCIP/CCIP wrap-up coordination
Get quotes today for a project-specific review before bidding a new commercial construction contract

Residential remodel contractors: a distinct risk profile from new construction

Residential remodel work carries a real, distinct exposure from new construction: the project is performed in or around an existing occupied home, which raises third-party injury exposure (a homeowner or their family present during construction) and property-damage exposure to portions of the home not part of the scope of work — a distinction general liability coverage should reflect explicitly, not assume is identical to ground-up new construction.

Read more

Remodel work also commonly uncovers unknown existing conditions — outdated electrical, undisclosed water damage, or in older homes, asbestos or lead — that a new-construction project on a vacant site wouldn't encounter, making pollution liability and change-order documentation genuinely relevant considerations for this specific trade.

Occupied-home work raises third-party injury and property-damage exposure new construction doesn't carry
Unknown existing conditions (electrical, water damage, asbestos, lead) are common on remodel work
Pollution liability and change-order documentation are genuinely relevant for this specific trade

Sequence shown, not a calendar

A remodel project, start to finish

Sequence shown — actual timing varies by jurisdiction, project size and trade.

1

Scope & Existing Conditions

Identify what's changing vs. what stays, and check for unknowns — electrical, water damage, hazardous materials in older homes.

2

Design & Permitting

Plans and permit scope sized to the actual work — often lighter than new construction, but still required for structural or systems changes.

3

Occupied-Space Coordination

Work sequenced around the home's continued occupancy — a real risk and scheduling factor new construction doesn't face.

4

Construction

Work proceeds with documentation of any existing conditions discovered mid-project.

5

Final Inspection & Closeout

Sign-off confirms the completed work matches approved plans and closes out any permits pulled.

When your own insurance holds up mobilization

A signed contract and a certificate of insurance aren't the same thing as being cleared to mobilize.

Read more

Most California GC and owner insurance exhibits ask for specific endorsements, not just a certificate — additional insured (AI) status, completed operations additional insured, primary and noncontributory wording, a waiver of subrogation, a per-project aggregate, a specific policy edition date, an auto additional insured endorsement, and excess coverage that follows form over the underlying policies. A certificate alone doesn't prove any of that is actually in place.

If the certificate keeps coming back rejected, the fix isn't a second copy of the same certificate — it's reading the actual insurance exhibit line by line, comparing it against the general liability and umbrella policies as issued, and getting the missing endorsements added before the deadline the GC or owner has already set. We track each requirement through to acceptance, not just to a certificate being sent.

Additional insured, completed-ops AI and auto AI are separate endorsements, not one box
Primary & noncontributory and waiver of subrogation rarely come standard
Per-project aggregates and specific edition dates are contract-driven, not automatic
We track each requirement to acceptance, not just to a certificate being sent

Read the insurance section before you sign, not after

The more expensive version of this problem shows up after the contract is already signed.

Read more

A California contractor commits to a $1M–$10M project, then finds out the carrier won't provide the completed-operations wording, the residential exposure, the height work, the pollution coverage, the design-build language, or the higher excess limit the contract actually requires — some California construction contracts call for substantial excess limits and multi-year completed-operations tails that not every program is built to satisfy.

That's a negotiation you want to have before you sign, not after. Send us the insurance requirements section of a contract before it's executed and we'll tell you plainly what's obtainable as written, what will cost more to obtain, and what genuinely needs to be renegotiated with the GC or owner — including on developer and subdivider projects, where project-specific requirements tend to be the most detailed — so the decision to sign is made with full information.

Some CA contracts require substantial excess limits and multi-year completed-ops tails
Design-build, residential, height and pollution exposure can each change carrier appetite
Review the insurance requirements section before the contract is executed
Know what's obtainable, what costs more and what needs renegotiation — before you sign

Before the transfer can work

Having the right endorsement is only half of it

A general illustration of common practice, not a description of any particular contract, carrier or policy.

What generally has to be in place

A written contract, in place before the loss. Blanket additional insured forms typically operate only where an agreement already requires the status — the wording is usually some form of "as required by written contract". An agreement signed after something has happened generally does not reach back, and a certificate on its own creates no obligation at all.
The endorsement actually attached to the policy. A certificate of insurance evidences that a policy existed on the day it was issued. It is not proof that any particular endorsement sits on that policy, which is why a requirement is commonly checked against the endorsement rather than the certificate.
The same named insured on both documents. The entity on the subcontract and the entity on the policy need to match. A DBA, a single-purpose entity for one project, or a renamed business are all ordinary reasons paperwork is rejected late, when there is least time to fix it.
Terms the policy itself allows. Availability differs by carrier, by line of insurance and by account. Whatever is granted is whatever the issued policy and the endorsements attached to it say — not what the contract asked for, and not what the certificate lists.

Two endorsements commonly named alongside additional insured status

Two endorsements commonly requested alongside additional insured status, the form number usually associated with each, and what each one generally does
EndorsementForm commonly usedWhat it generally does
Primary and non-contributoryoften CG 20 01Commonly decides whether the downstream policy responds first, or shares with the upstream party’s own cover. Usually keyed to a written contract requiring it.
Waiver of subrogationCG 24 04Gives up the insurer’s right to recover from the upstream party after paying a claim. Frequently named alongside additional insured status rather than instead of it.

From our case files: lessons general contractors have paid for

General contractors carry their subs' mistakes and their own.

Read more

One GC we work with had no certificate from a roofing sub and ended up defending a leak lawsuit brought by the home's next owners (case study 1). Another was working on an upper floor of a commercial building when a pipe burst and water reached the suite below, damaging electronics and medical equipment; the claim was paid, but the carrier declined to renew and the replacement coverage cost roughly 90% more (case study 5).

A third file shows a permit stalling on paperwork alone: a city building department turned away a GC's blanket AI and blanket waiver endorsements because it required its own name and exact language on scheduled endorsements, and nothing moved until we called the city and then obtained the right forms from the carrier (case study 12).

Frequently asked questions

27 questions — start typing to filter

Do I need separate policies for each trade I subcontract to?

No — as the general contractor, your own general liability, workers comp and umbrella coordinate around your operations. Subcontractors carry their own policies, verified through your risk-transfer process.

What's the biggest insurance mistake growing GCs make?

Letting subcontractor certificate tracking lapse as the number of active subs grows, and not reviewing aggregate limits and bonding capacity against the full current project list rather than just the newest job.

Does my GL policy's aggregate limit apply per project or across all projects?

By default, many policies share one aggregate limit across the entire policy period regardless of project count — a per-project aggregate endorsement addresses this specifically if you're running multiple simultaneous projects.

Do I need a separate umbrella policy as a general contractor?

Many GCs do, especially once project size grows — umbrella coverage extends liability limits above the underlying GL, auto and employer's liability policies for a lower relative cost than raising each underlying limit.

How do public works requirements differ from private commercial work?

Public works typically adds DIR registration, prevailing wage compliance and certified payroll reporting on top of standard insurance and bonding requirements — confirm all of it before bidding, not after award.

What should I check before adding a new subcontractor to a project?

Their current certificate of insurance, the specific endorsements your contract requires (additional insured, waiver of subrogation, primary and noncontributory), and the expiration dates — not just whether they say they're insured.

How do I know if my current program is actually coordinated or just several separate policies?

Ask whether effective dates, named insureds and classifications line up across your GL, auto, workers comp and umbrella policies — a broker managing them as one program should be able to answer that directly.

Does this cover residential, commercial, new construction and remodeling contractors the same way?

The core coverage lines are the same — general liability, workers compensation, commercial auto, builders risk and bonds — but the actual limits, classifications and endorsements differ by what's being built. A residential general contractor doing new construction has a different risk profile than a commercial general contractor, and a remodeling contractor working inside occupied homes has different exposures than either — completed operations and "resides in" exclusions in particular need to be checked against the specific type of work being performed, not assumed to be identical across all four. Searching for general contractor insurance near me usually turns up national directories first — working with a California-licensed broker directly, rather than a lead-generation site, typically gets a more accurate quote faster.

Do you write insurance for specialty subcontractor trades like fencing, landscaping, welding, tile or well drilling contractors?

Yes — alongside general contractor packages, we place coverage for the specialty trades GCs coordinate on a project, including fencing, landscaping, welding, reinforcing steel, tile, sign, well drilling and asbestos abatement contractors, each with its own trade-specific risk profile. See our exclusions-by-CSLB-classification breakdown in the construction insurance lines overview for the specific exposures carriers underwrite for each trade, or get a quote today for your specific classification.

If I'm building infrastructure under a developer's Subdivision Improvement Agreement, does that change what my GL or bond needs to look like?

It can. Work performed under a developer's Subdivision Improvement Agreement (SIA) often flows down specific additional insured, indemnity and bonding requirements from the jurisdiction through the developer to the GC actually performing the infrastructure work — confirm the SIA's specific insurance and bonding language with the developer before starting rather than assuming your standard GL and bond program already matches it. See our Subdivision Improvement Agreement vs. Development Agreement breakdown for how these requirements are structured.

Does new commercial construction need different coverage than commercial renovation work?

Generally yes — new commercial construction needs builders risk and general liability limits sized to the full ground-up project value and the structure's eventual occupancy scale, while renovation work adds its own occupied-building liability considerations. Confirm the actual project value and any owner/lender-required limits before assuming one standard package fits both.

Do residential remodel contractors need different coverage than new home builders?

Yes, in real ways — remodel work happens in or around an occupied home, raising third-party injury and existing-property damage exposure that new construction on a vacant site doesn't carry, and often uncovers unknown existing conditions (electrical, water damage, asbestos, lead in older homes) worth discussing with your broker directly.

Do I need separate vehicle coverage if I already have a general contractor insurance package?

Yes — a GC's liability and property coverage doesn't extend to vehicles. CA Business Vehicle Insurance covers pickups, service trucks and trailers titled to the business, and it's typically written as its own policy alongside the GC package rather than bundled into it.

Should a general contractor carry pollution coverage even if a sub is doing the dirt work?

Often worth reviewing — a GC can still be named in a pollution claim regardless of which sub actually disturbed the soil. Construction Pollution Liability Insurance covers what's typically included, since coverage and availability vary meaningfully by carrier.

Where can I find more detailed guidance beyond this coverage page?

CA Construction Contractor Resources is the hub for the deeper guides on this site — bonding, public works compliance, underwriting readiness and more, organized by topic rather than by policy type.

Should I use one contractors bonding and insurance company, or buy bonds and insurance separately?

You can buy them from different sources, but most CA contractors find it simpler to work with one contractors bonding and insurance company that handles both — it keeps your license bond, GL, workers comp and any project bonds coordinated instead of managed across separate vendors with no visibility into each other.

What is home under construction insurance, and is it the same as homeowners insurance?

No — home under construction insurance, more commonly called builders risk, is a project-specific policy covering the structure itself while it's being built; a standard homeowners policy generally doesn't apply until the home is completed and occupied.

Does a GC's policy cover a tree service sub working under the old D-49 classification?

The GC's own policy doesn't extend to a sub's operations — the tree service sub needs its own coverage regardless of classification name. See our C-49 tree and palm contractor insurance guide for the recent classification change from C-61/D-49 to C-49 and what it means for a sub's certificate.

Does a GC's policy cover welding work performed by a sub?

No — a welding subcontractor needs its own coverage matched to the real fire and hot-work exposure of that trade, regardless of what the GC's own policy carries. See our welding contractor insurance guide for what a welding sub actually needs.

What's the difference between a certificate of insurance and being cleared to mobilize?

A certificate is a summary — it doesn't by itself prove that additional insured status, completed operations additional insured, primary and noncontributory wording, a waiver of subrogation or any other contract-required endorsement is actually attached to the policy. Being cleared to mobilize means the actual endorsements have been issued and accepted by the GC or owner, not just that a certificate was sent.

Can I have my contract's insurance requirements reviewed before I sign it?

Yes — as part of putting together your quote, send us the insurance requirements section of a contract before it's executed. As broker availability allows, we'll compare it against what your program can provide, flag anything that isn't obtainable as written, and outline what it would take to satisfy it, so you're deciding with full information rather than finding out after the fact.

What does general contractor liability insurance actually cover?

General contractor liability insurance (general liability) responds to third-party bodily injury and property damage claims arising from your operations or completed work — the foundation of most GC insurance programs, but rarely the only coverage a real project needs alongside it (workers comp, auto, builders risk and often umbrella).

What drives contractor insurance cost for a California general contractor?

Revenue, payroll, subcontractor use, classification accuracy and loss history are the biggest factors — not company size alone. Two contractors with similar revenue can see meaningfully different premiums based on how accurately their operations are classified and whether their loss history is documented with context.

How fast can I get a general contractor insurance quote?

Turnaround depends on submission completeness — a clean submission with real operational detail, loss runs if applicable, and any specific contract requirements moves faster than a bare request. Call 844-978-7283 or request a quote with as much detail as you have.

Do concrete, public works and commercial construction contractors get more insurance options over time?

Yes. Gleason Insurance Brokers has access to more markets for concrete contractors, public works contractors and commercial construction contractors once a business has at least four years of operating history, on top of the usual underwriting factors like bonding capacity, safety program and loss history. Call 844-978-7283 to review your options.

Should I use a third-party administrator to track subcontractor certificates on a large project?

On an OCIP, CCIP or a big project-specific liability program, generally yes — most GCs can't realistically keep every subcontractor's certificate, endorsement and coverage term current by hand once a job gets busy, which is exactly when things get missed. A TPA's whole job is catching that before it becomes a problem: a gap that surfaces only after a claim is filed can get the claim denied outright, or turn into an audit finding that charges an under-documented sub's payroll back to you. It's an added line-item cost, but a cheap one next to either outcome.

Is a third-party administrator only worth it on a required program?

Not necessarily. Some general contractors arrange this kind of certificate and endorsement tracking and subcontractor compliance monitoring even when their program doesn't require it, so carrier terms and conditions and the risk transfer process get monitored without adding that burden to their own office. It's generally available at a fairly reasonable added cost relative to the time it saves.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Explore Related Coverage and Contractor Resources

Related coverage
Guides, trades and resources

Updated October 12, 2026