
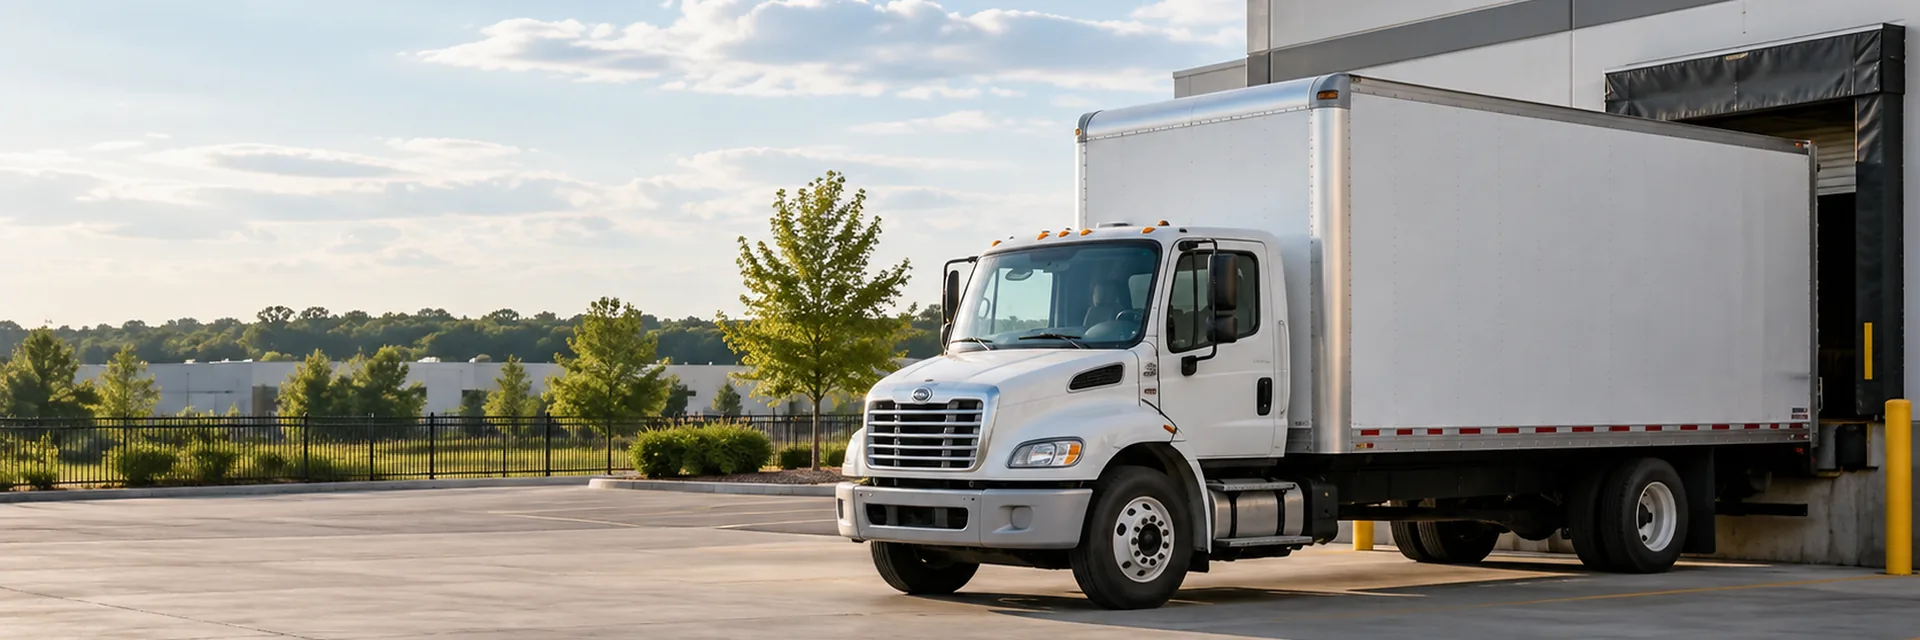


What counts as a box truck, and why it matters for insurance
Box trucks — also called straight trucks or cube trucks — range from smaller Class 3 vehicles used for local delivery up through Class 6-7 trucks used for moving, freight and distribution, and that weight range matters directly for insurance and licensing: a commercial driver's license generally becomes a factor once a vehicle's gross vehicle weight rating crosses 26,001 lbs, though exact requirements depend on the specific vehicle and operation.
Unlike a flatbed or pickup, the cargo box is fully enclosed — which protects freight from weather but doesn't eliminate cargo risk, since an enclosed, unmarked box can be an equally real theft target precisely because what's inside isn't visible from outside. If you are launching a box truck operation under your own authority, see insurance for new trucking businesses. Operators who move up from box trucks to a tractor and trailer face different rating, cargo limits and DOT requirements, explained on tractor-trailer insurance. If you run both, our fleet site explains how cargo van and box truck insurance differ.
Common box truck operations
Moving and relocation, furniture and appliance delivery, last-mile and parcel delivery, catering and food-service delivery, and contractors hauling tools, materials or equipment between job sites all rely on box trucks — and the right coverage looks different depending on which of these an operation runs, since the cargo value and handling exposure aren't the same for a furniture mover as they are for a parcel delivery route.
Confirm the policy reflects the actual operation rather than a generic box truck assumption — a contractor hauling its own tools and materials carries a different cargo profile than a business moving customer-owned furniture and appliances.
Showing 1 of 6
Commercial auto and cargo coverage built for box truck operations
Liability sized to the real exposure of a loaded box truck, physical damage coverage for the truck itself, and cargo insurance that reflects what's being hauled are the core of the program — and cargo limits deserve a real look rather than a default figure, since a box truck full of appliances, retail goods or specialized equipment can carry more value than the empty vehicle itself.
Operations moving customer-owned property — furniture, appliances, business inventory — carry a liability dimension standard cargo coverage doesn't always fully address; confirm directly whether the program needs to account for third-party property in the box, not just the truck owner's own goods.
Liftgates and loading equipment
A hydraulic liftgate is common equipment on a box truck used for delivery or moving work, and it's a real factor on two fronts: it's equipment with its own repair and replacement cost, and loading-dock and liftgate operation is a well-documented source of injury claims — a load shifting, a liftgate malfunctioning, or a worker caught between the gate and the truck.
Confirm the liftgate itself is covered under the vehicle's physical damage coverage, and that workers compensation and general liability both reflect the real loading and unloading exposure the operation has, not just the driving exposure.
Common box truck claims and exposures
Cargo shifting or being damaged inside the box during transit still happens even though the load is enclosed — freight that isn't braced or secured inside the box can shift on turns and stops the same way an improperly secured open load can, just out of sight.
Backing incidents, tight urban loading zones, and dock or liftgate injuries are common box truck exposures alongside standard collision risk, and theft of cargo or tools left in an unattended box truck is a real, recurring loss pattern worth confirming coverage for directly.
Illustrative only — this describes a typical pattern, not an actual claim or a guaranteed outcome. Coverage determinations depend on the specific policy and facts involved; for a real, case-specific question, consult a licensed attorney or the appropriate authority having jurisdiction.
Getting box truck coverage and compliance aligned
Confirm which of USDOT, a California CA number and a Motor Carrier Permit apply to the specific vehicle and operation — the same registration framework that applies to any California commercial truck applies to a box truck based on its actual weight and use — and make sure cargo limits, liftgate coverage and driver qualification are all coordinated together.
Gleason Insurance Brokers places commercial auto and cargo coverage for box truck operations across California — call 844-978-7283 or request a quote with the actual vehicle, typical cargo and equipment detail.
Frequently asked questions
9 questions — start typing to filter
Do I need a USDOT number for a box truck?
Possibly — USDOT requirements depend on vehicle weight, interstate operations, cargo and other federal factors, the same as any commercial trucking operation. Verify applicability with FMCSA.
Do I need a CDL to drive a box truck in California?
It depends on the vehicle's gross vehicle weight rating — a commercial driver's license generally becomes a factor once GVWR crosses 26,001 lbs, with some exceptions. Confirm the specific requirement for your vehicle with California DMV.
Is cargo inside my box truck automatically covered, or do I need a separate policy?
Not automatically in every case — confirm directly whether motor truck cargo coverage is included and whether the limit reflects the real value of what's typically hauled, including any customer-owned property.
Is a liftgate covered under my box truck policy?
Confirm directly — a liftgate is real equipment with its own repair and replacement cost, and it should be reflected in physical damage coverage rather than assumed to be automatically included.
Do moving companies need additional registration in California?
Businesses that move customer-owned household goods commercially in California can have registration requirements beyond standard motor-carrier registration. Confirm current requirements directly with California DMV before operating.
Does an enclosed box reduce my cargo insurance cost compared to a flatbed?
Not necessarily — cargo pricing reflects the value and type of freight hauled and the operation's claims history, not just whether the load is enclosed. Request a quote with the actual cargo detail for an accurate comparison.
Show 3 more questions
What's the difference between a box truck and a straight truck?
They're generally the same thing — "box truck," "straight truck" and "cube truck" all describe a single vehicle with an enclosed cargo body mounted on the chassis, as opposed to a tractor-trailer with a separate towed trailer.
Do people search business auto insurance or commercial auto insurance for a box truck?
Both — they're the same coverage. Business auto insurance and commercial auto insurance are interchangeable names for a policy covering vehicles used for business rather than personal use; for a box truck specifically, what changes pricing is cargo type, delivery radius, and whether it's driven by an employee or an owner-operator.
If I take a box truck out of service, am I still responsible for premium?
It depends on whether that truck carries a filing at all. A box truck under the weight and use thresholds that bring a Motor Carrier Permit or federal authority into play can usually come off the policy when it goes out of service. One that does carry a filing is different: the filing comes off on the regulator's timetable once it has been notified, and premium can remain due through that notice period. Box trucks sit close to those thresholds, so confirm the actual gross vehicle weight rating and how the truck is used rather than assuming.
California · General information only, not legal advice. Requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer
Reviewed by David Gleason, Principal — October 27, 2026