Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

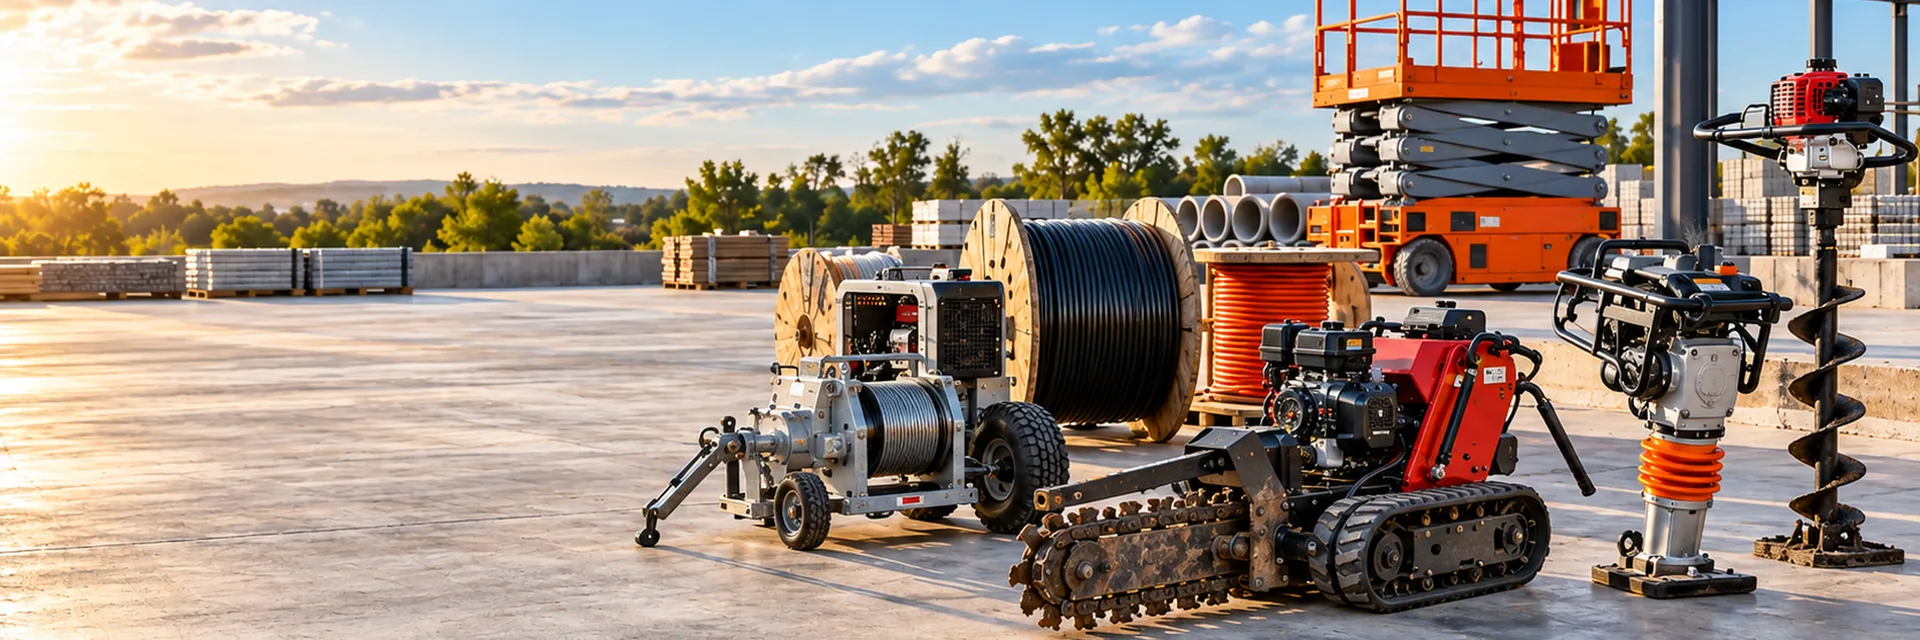
A trailer-mounted winch, cable reels, a walk-behind trencher, a rammer compactor, an auger and a scissor lift on a job site — contractor equipment and inland marine insurance

California commercial insurance

Contractor Equipment & Inland Marine CA

844-97-USAVE

General liability doesn't cover damage to your own tools and equipment — that's what inland marine coverage is for, and it's one of the more commonly under-insured lines for contractors who assume it's bundled in somewhere else.

  • Scheduled Equipment
  • Small Tools
  • Coinsurance Exposure

Reviewed by David Gleason, Principal — October 11, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Contractor Equipment / Inland MarineMobile tools, equipment and property away from premises

What it is

Inland Marine is commonly used for tools, equipment and certain mobile property that moves between locations or jobsites.

Why businesses like yours commonly carry it

Contractors frequently move tools, testing equipment and mobile machinery among jobsites.

Possible coverage gap

General Liability should not be assumed to insure the business's own tools and equipment against theft or physical damage.

Learn more about Contractor Equipment / Inland Marine
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Contractors commonly use email, electronic banking, project platforms, payroll systems and cloud document storage.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for contractors

Exposure-Dependent Coverages

Installation FloaterMaterials awaiting or undergoing installation

What it is

An Installation Floater may cover certain materials and equipment in transit, temporary storage and during installation, subject to the policy.

Why businesses like yours commonly carry it

Businesses responsible for materials before final installation commonly consider this coverage.

Possible coverage gap

A basic liability policy generally should not be assumed to cover the insured's materials against physical loss before installation is complete.

Learn more about Installation Floater
Builder's RiskProject property during construction

What it is

Builder's Risk may insure covered buildings, materials and certain project property while construction is underway.

Why businesses like yours commonly carry it

Owners, developers and contractors commonly consider it when a structure or major renovation is exposed during construction.

Possible coverage gap

Commercial Property and General Liability are not automatic substitutes for course-of-construction property coverage.

Learn more about Builder's Risk
Contractors Pollution LiabilityPollution conditions and cleanup liability

What it is

Pollution Liability may address covered cleanup costs and third-party injury or property damage arising from pollution conditions.

Why businesses like yours commonly carry it

Businesses working with fuels, chemicals, soil, water, demolition or environmental conditions may have pollution exposures.

Possible coverage gap

Standard General Liability commonly contains pollution exclusions or limitations.

Learn more about Contractors Pollution Liability
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Why equipment needs its own coverage

General liability responds to third-party claims, not damage to a contractor's own property.

Read more

Tools, mobile equipment, and materials in transit are typically covered — if covered at all — under a separate inland marine or contractor's equipment policy, not the liability policy.

Equipment values can run higher than expected once tools, attachments, and mobile equipment are totaled — an accurate schedule matters both for limits that reflect the values you intend to insure and to avoid a coinsurance penalty at claim time if the policy limit doesn't reflect actual values.

GL covers third-party claims, not your own equipment
Inland marine/equipment coverage is separate and often needed
Total equipment value is easy to underestimate
An outdated schedule risks a coinsurance penalty at claim time
Several trades carry especially significant mobile-equipment exposure: see our Tree Service, Fiber Optic / Low Voltage, Directional Drilling & Trenchless and Welding guides for trade-specific equipment considerations

What inland marine typically covers

Depending on the policy, coverage can extend to owned tools and equipment, mobile equipment not registered as a vehicle, property in transit between jobsites, and sometimes rented or leased equipment — though rented equipment coverage varies by policy and should be confirmed specifically.

Read more

Some policies cover equipment on an actual cash value basis, others on replacement cost — this distinction matters significantly for older equipment and should be understood before a claim, not discovered during one.

A 2020 file of ours shows what the paperwork is worth: a plumbing contractor near Antioch lost water jetting equipment and tools worth about $19,000 to a theft from a service van and truck at the shop, and the claim paid because a scheduled list was already on file with the carrier and a police report was filed straight away. Read the full case.

Owned tools, mobile equipment and property in transit commonly covered
Rented/leased equipment coverage varies — confirm specifically
Actual cash value vs. replacement cost is a meaningful distinction
Understand valuation basis before a claim, not during one
HVAC and mechanical contractors setting rooftop units, chillers or large commercial condensers often add crane/rigging equipment to the mix — see our HVAC / Mechanical / Refrigeration Contractor Insurance California guide for how that's typically covered

Keeping the equipment schedule current

Newly purchased equipment should be added to the schedule as it's acquired, not at the next renewal — a gap between purchase and scheduling leaves genuinely uninsured equipment exposed in the interim.

Read more

Equipment that's sold, retired, or no longer in service should be removed too — an accurate, current schedule keeps both coverage and pricing aligned with what's actually owned and in use.

Add new equipment to the schedule as it's purchased
A gap between purchase and scheduling leaves real exposure
Remove sold or retired equipment from the schedule
An accurate schedule keeps pricing aligned with actual holdings

Rented and leased equipment considerations

Contractors who regularly rent or lease equipment for specific projects should confirm whether their inland marine policy extends to rented equipment or whether the rental agreement itself requires separate coverage — this is a common point of confusion and a common gap.

Read more

Some equipment rental agreements include their own damage waiver options; understanding whether that duplicates or is actually needed alongside your own coverage avoids paying for the same protection twice, or having neither.

Confirm whether your policy extends to rented/leased equipment
Rental agreements sometimes require separate coverage
Understand any rental damage waiver options offered
Avoid either duplicate coverage or an actual gap

A realistic equipment theft or damage scenario

A skid steer and a trailer full of hand tools are stolen from a jobsite over a weekend — a loss that a standard commercial property policy, written around a fixed business location, typically doesn't cover at all, since the equipment wasn't at the insured premises when the loss occurred.

Read more

Inland marine exists specifically for equipment that moves between jobsites — scheduling equipment by value (not just a blanket limit) is what determines whether a specific piece of stolen or damaged equipment is actually reimbursed at something close to its real replacement cost.

This is offered as a general, illustrative example of how this type of situation commonly plays out — not a specific case, and not a promise of how any real claim would be decided. For an actual situation, the specific policy language and a licensed attorney or the relevant regulatory authority are the right resources, not this page.

Standard property policies are location-based and often miss off-site equipment
Inland marine is written specifically for equipment that moves between jobs
Scheduling equipment by value matters more than a blanket limit
Unscheduled or under-valued equipment is a common source of claim disputes

Getting equipment coverage right

Provide a current equipment list with approximate values, note any regularly rented equipment, and flag any high-value or specialized items so the quote reflects actual holdings.

Read more

Gleason Insurance Brokers places contractor equipment and inland marine coverage across California — call 844-978-7283 or request a quote with your current equipment schedule.

Provide a current equipment list with approximate values
Flag high-value or specialized equipment specifically
Note any regularly rented equipment
Reach a broker on 844-978-7283, or request a quote

What a rental company's own contract typically requires

Beyond confirming a policy extends to rented equipment, the rental agreement itself is usually where the real requirement lives.

Read more

Most equipment rental contract insurance requirements name the renting contractor as responsible for the equipment from pickup to return — covering physical damage regardless of fault while it's in the contractor's care, custody and control — and many rental companies specifically require proof of that coverage, sometimes with the rental company itself named as loss payee, before releasing the equipment at all.

Rented equipment physical damage coverage under an inland marine policy typically responds on the contractor's own equipment; whether it extends automatically to equipment merely rented or leased from others is a policy-specific question, not a given — some inland marine forms include it by definition, others require a specific rented/leased equipment endorsement to actually pick it up. A contractor that assumes broad equipment coverage automatically includes rented equipment can find out otherwise only after a piece of rented machinery is damaged or stolen and the claim gets denied.

This matters more for contractors with larger or more frequent equipment needs — renting a compactor for a weekend carries a different scale of exposure than a contractor regularly renting excavators, cranes or specialty equipment for active projects. Larger contractors with real ongoing rental volume are exactly the audience this coverage question is built for, not the occasional small tool rental.

Rental contracts often make the contractor responsible for physical damage from pickup to return
Some rental companies require proof of coverage, occasionally naming themselves as loss payee
Rented equipment physical damage may or may not be automatic under a standard inland marine form
Matters most for contractors with real, ongoing rental volume, not an occasional weekend rental
See our Builders Risk guide for how builders risk and an installation floater typically work together on an active project

Equipment coverage by contractor type

Equipment exposures differ by trade, so these pages cover the equipment each type of contractor commonly runs.

Frequently asked questions

16 questions — start typing to filter

Do you offer insurance for contractor equipment?

Contractors equipment or inland marine coverage may be available for qualifying businesses.

Does contractor equipment insurance cover rented equipment?

Potentially — policies may offer coverage for certain rented, leased or borrowed equipment, but limits and conditions vary.

What types of property can inland marine insurance cover?

Depending on the policy, inland marine coverage may be used for contractor equipment, tools, mobile equipment, certain property in transit, rented or leased equipment, and other qualifying movable property — coverage depends on the actual policy.

What is an admitted insurance company?

An admitted insurer is licensed by the state to transact the applicable insurance business and is subject to the state's admitted-market regulatory framework.

What is a non-admitted or surplus-lines insurance company?

A non-admitted insurer is not licensed as an admitted insurer in that state but may provide insurance through the surplus-lines market when applicable requirements are satisfied. "Non-admitted" does not automatically mean unreliable or unregulated.

Will a non-admitted carrier pay my claim?

Claim coverage depends on the actual policy, facts of the claim and insurance company — admitted versus non-admitted status by itself does not determine whether a particular claim will be paid.

How reliable are non-admitted insurance companies?

Evaluate the individual insurer — financial strength, claims capability, policy wording, experience and reputation are important considerations. Many specialized, difficult or higher-hazard commercial risks are insured through the surplus-lines market.

Is this the same as contractors equipment insurance, contractor tool insurance, or contractors material insurance?

Yes — inland marine is the formal insurance-industry name for this coverage. Contractors and business owners more often search for it as contractors equipment insurance, contractor tool insurance, or contractors material insurance. All describe the same protection for tools, equipment and materials in transit or stored at a job site, not just equipment permanently fixed at one location.

Should a business vehicle insurance quote include the tools and equipment stored in the truck?

Not automatically — a business vehicle insurance quote typically covers the vehicle itself; tools and equipment carried inside it are usually a separate inland marine coverage line, worth confirming isn't assumed to be included.

Does my inland marine policy automatically cover equipment I rent from others?

Not always — it depends on the specific policy form. Some inland marine policies extend automatically to equipment rented or leased from others; others require a specific rented/leased equipment endorsement to pick up that exposure at all. Separately, the rental agreement itself usually makes the renting contractor responsible for physical damage from pickup to return, and some rental companies require proof of coverage — sometimes naming themselves as loss payee — before releasing the equipment. Confirming both sides (the rental contract's requirement and whether the policy actually responds) avoids a gap.

What's the difference between rented equipment insurance and leased equipment insurance for a contractor?

In practice, rented equipment insurance and leased equipment insurance for a California contractor raise the same underlying question: does the inland marine policy extend to contractor equipment rented from others, or does the rental/lease agreement itself require separate proof of coverage? Short-term rentals and longer equipment leases are both commonly excluded from a standard schedule unless specifically endorsed — confirm which applies before assuming either is automatically covered.

Are directional drilling rigs covered the same way as standard construction equipment?

Not automatically — drilling rigs represent significant, specialized equipment value that needs coverage structured for this specific type and scale of equipment. See our horizontal directional drilling insurance California guide for how this is typically handled.

Do portable welding rigs need different equipment coverage than standard tools?

Yes — a portable welding rig represents real, mobile equipment value moving between job sites, similar in kind to other specialized mobile equipment. See our welding contractor insurance guide for how this is typically covered.

Is inland marine insurance the same as construction equipment insurance?

In practice, yes — "inland marine insurance" is the technical policy category, and "construction equipment insurance" is what most contractors actually call the coverage that protects owned and rented equipment while it's away from a fixed location, in transit, or at a job site. Both terms point to the same coverage.

Does Gleason have strong markets for tools and equipment insurance?

Yes. Gleason Insurance Brokers has strong, extremely competitive inland marine markets for contractors equipment insurance, covering owned and rented tools and equipment used on and off the jobsite. Call 844-978-7283 for a quote.

Are Gleason's inland marine and equipment insurance carriers affordable?

Not every inland marine carrier prices equipment risk the same way, and we work with several known for affordable, competitive terms in this space. Where a specific account actually lands on price comes down to real variables — equipment type and value, theft-prevention measures, jobsite security, and loss history chief among them. Call 844-978-7283 so we can match your equipment schedule to the right market.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Explore Related Coverage and Contractor Resources

Related coverage
Guides, trades and resources

Updated October 11, 2026