Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

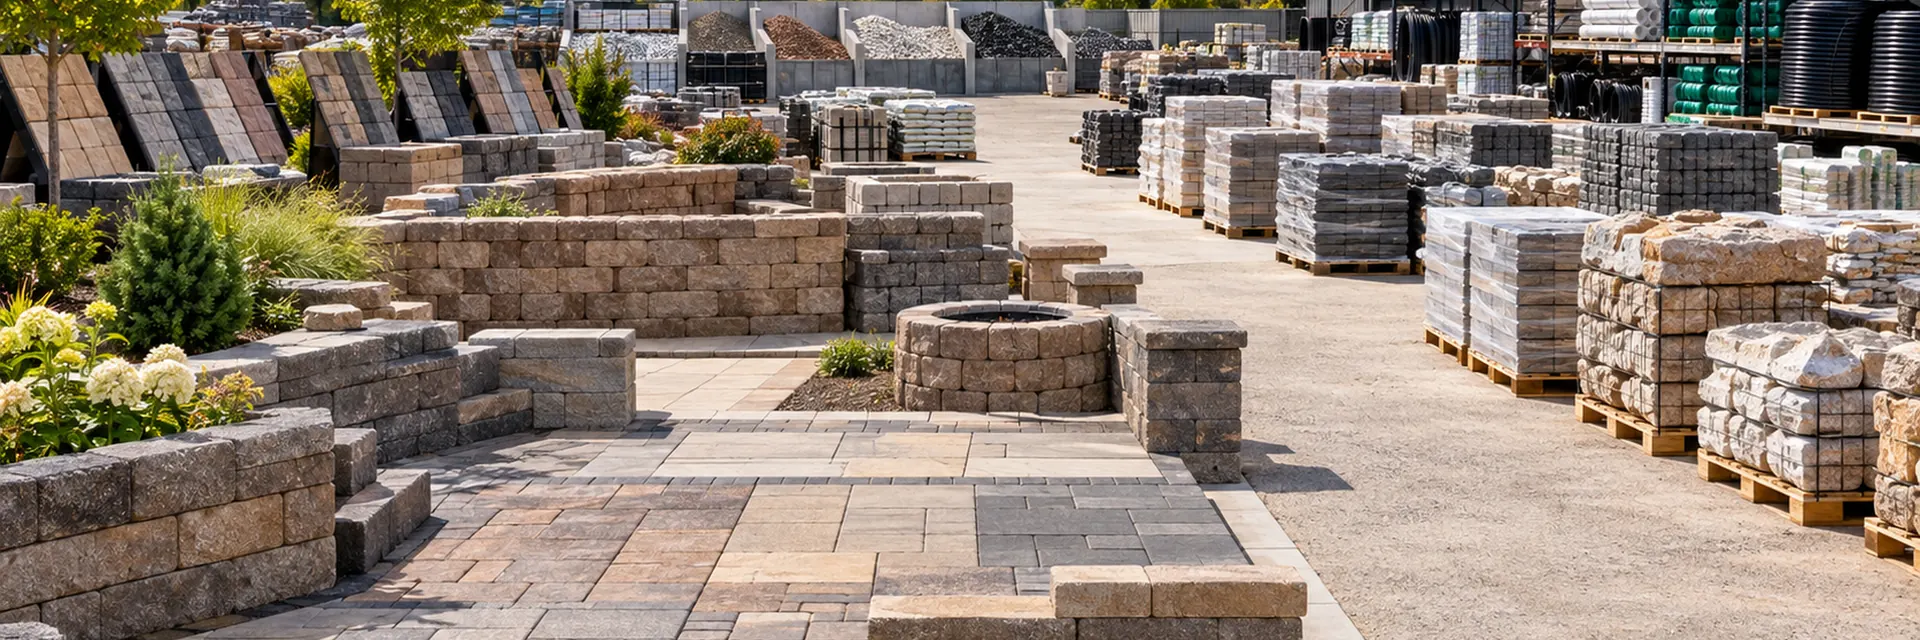
A landscape and hardscape supply yard with paver and retaining wall displays laid out in front of banded pallets of block, stone and bagged material — landscape hardscape supplier insurance california

California commercial insurance

Landscape & Hardscape Supplier Insurance CA

844-97-USAVE

Landscape and hardscape suppliers can stock stone, pavers, soil, irrigation components, plants and retaining-wall systems across open yards.

  • Outdoor Property
  • Material Handling
  • Delivery Exposure

Reviewed by David Gleason, Principal — October 11, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability
Business Owners Policy / Commercial PackageLiability and property components evaluated together

What it is

A Business Owners Policy commonly combines liability and property coverages for eligible businesses. A Commercial Package Policy may combine multiple commercial coverage parts depending on the account and carrier.

Why businesses like yours commonly carry it

Businesses with premises, contents, inventory or other property exposures may ask GIB to evaluate whether liability and property components can be packaged where appropriate.

Possible coverage gap

Eligibility, included coverages and package structure vary by carrier. Commercial Property may also be written separately rather than as part of a package.

Learn more about Business Owners Policy / Commercial Package

Commonly Added Based on Operations

Commercial AutoBusiness vehicles, drivers and physical damage

What it is

Commercial Auto may address liability arising from covered business vehicles and, when selected, physical damage and other vehicle-related coverages.

Why businesses like yours commonly carry it

Businesses that own or regularly use vehicles may need a policy structured around business use, drivers and vehicle schedules.

Possible coverage gap

Personal auto policies may restrict or exclude business use, and General Liability is generally not a substitute for auto liability.

Learn more about Commercial Auto
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Suppliers invoice contractors constantly and are among the businesses most often impersonated in payment-change fraud.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for suppliers and distributors

Exposure-Dependent Coverages

Equipment BreakdownMechanical, electrical and pressure-system breakdown

What it is

Equipment Breakdown may address certain sudden mechanical, electrical or pressure-system breakdown losses, subject to the policy.

Why businesses like yours commonly carry it

Businesses dependent on refrigeration, production, HVAC, electrical or other critical equipment commonly consider it.

Possible coverage gap

Standard property forms may not address every internal mechanical or electrical breakdown.

Learn more about Equipment Breakdown
Commercial Crime / FidelityEmployee theft and certain fraud losses

What it is

Commercial Crime may address certain covered theft, fraud and funds-transfer losses, depending on the selected insuring agreements.

Why businesses like yours commonly carry it

Businesses handling money, inventory, payments or account access commonly consider crime coverage.

Possible coverage gap

Property and cyber policies do not necessarily cover every employee theft or social-engineering loss.

Learn more about Commercial Crime / Fidelity
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Outdoor Property

Wildfire, theft, weather and irrigation failure affect outdoor inventory differently from warehouse stock.

Wildfire, theft, weather and irrigation failure affect outdoor inventory differently from warehouse stock

Material Handling

Loaders and forklifts interact with customers and delivery vehicles.

Loaders and forklifts interact with customers and delivery vehicles

Delivery

Dump trucks, flatbeds and boom delivery increase auto severity.

Dump trucks, flatbeds and boom delivery increase auto severity

Product Allegations

Retaining-wall and irrigation products can be named in performance disputes.

Retaining-wall and irrigation products can be named in performance disputes

Middle-Market Account Profile

A middle-market landscape/hardscape yard should split live plant inventory from stone, pavers, soil, irrigation, retaining-wall systems and masonry products. Outdoor storage, loader/forklift traffic, wildfire, water supply and dump/flatbed delivery should be documented separately.

A middle-market landscape/hardscape yard should split live plant inventory from stone, pavers, soil, irrigation, retaining-wall systems and masonry products
Outdoor storage, loader/forklift traffic, wildfire, water supply and dump/flatbed delivery should be documented separately

Coverage Priorities for This Niche

The property program may need different treatment for living stock versus durable building material. GL/products, yard liability, equipment coverage, delivery auto, cargo, WC and excess should follow the actual operation. Business interruption should consider seasonal inventory and alternate suppliers. Suppliers that also sell pool equipment, chemicals and spa products can see insurance for pool and spa suppliers. Outdoor yard inventory, forklifts and delivery trucks are covered in more depth in our article on building supplier fleet, cargo and yard risk.

The property program may need different treatment for living stock versus durable building material
GL/products, yard liability, equipment coverage, delivery auto, cargo, WC and excess should follow the actual operation
Business interruption should consider seasonal inventory and alternate suppliers

Underwriting Questions Before Marketing the Account

Questions worth reviewing before marketing or binding this account:

What portion of inventory is live plant material?
What is the peak outdoor stock value?
Are loaders used to load customer vehicles?
Does the business deliver with dump/flatbed trucks?
Are retaining-wall systems or engineered products a material share of sales?

Coverage Gaps Worth Checking

Living plants, stone, pavers, irrigation products and bulk soil do not behave the same way in a property loss. The program should distinguish perishable/living stock, outdoor durable inventory and mobile yard equipment. Delivery auto should also reflect dump operations, forklift loading and crane/boom work where applicable.

Living plants, stone, pavers, irrigation products and bulk soil do not behave the same way in a property loss
The program should distinguish perishable/living stock, outdoor durable inventory and mobile yard equipment
Delivery auto should also reflect dump operations, forklift loading and crane/boom work where applicable

What a Strong Submission Looks Like

Show inventory by category, peak seasonal plant values, wildfire controls, irrigation/water dependency, loaders/forklifts, delivery fleet, top contractor customers and any engineered retaining-wall systems. For nurseries, clarify how quickly living stock could be replaced after a catastrophe.

For nurseries, clarify how quickly living stock could be replaced after a catastrophe

Seasonal and Catastrophe Considerations

Inventory can change dramatically by season, especially where live plant stock is material. Property values should reflect peak season rather than an average month. California wildfire, wind and water restrictions can also affect both stock and business income. For hardscape yards, heavy product, customer pickup and loader operations make premises safety important. The broker should understand whether staff only loads materials or also recommends engineered retaining or drainage systems.

Inventory can change dramatically by season, especially where live plant stock is material
Property values should reflect peak season rather than an average month
California wildfire, wind and water restrictions can also affect both stock and business income
For hardscape yards, heavy product, customer pickup and loader operations make premises safety important

Frequently asked questions

8 questions — start typing to filter

Is outdoor stock covered the same as indoor inventory?

Not always — outdoor hardscape and landscape material needs to be specifically addressed for weather and theft exposure, since not every commercial property form treats yard stock the same as indoor inventory.

Are plants insured like building materials?

Living inventory can require different treatment.

Does delivery create cargo exposure?

Yes — pavers, block and landscape material in transit need their own cargo or inland marine limit reflecting real per-load values.

Are retaining-wall products a liability exposure?

They can be — a retaining wall's structural failure can be blamed on the supplied block, paver or engineered system, creating a products liability claim independent of the installing contractor's own work.

Do loaders need equipment coverage?

Yes — yard loaders and material handlers are mobile equipment that typically need inland marine or equipment coverage distinct from the building and inventory property form.

How much does wildfire exposure affect a landscape supplier’s property insurance?

A great deal across much of California, and more than operators expect for a yard rather than a structure. Bulk mulch, bark and timber stock are combustible and usually held outdoors in volume, which is a different property conversation from an enclosed building. Location drives it: a yard inside or near a high fire hazard severity zone may see reduced capacity, higher deductibles, or a requirement for defensible space and separation between stockpiles before a carrier will quote.

Should irrigation-related products be reviewed separately?

Yes — a failed irrigation component that causes water damage or erosion is a distinct products liability scenario from a hardscape material failure and should be described separately in the submission.

Does storing fertilizer and herbicide change what a property carrier wants to see?

It commonly does. Bulk fertilizer, herbicide and soil amendments bring both a fire and a pollution dimension that plain nursery stock does not, and some products carry storage and separation requirements of their own. Property underwriters frequently ask where the chemicals sit relative to the rest of the yard, what containment exists, and whether the quantities trigger a hazardous materials business plan with the local certified unified program agency. On the liability side, a release that reaches soil or storm drains is generally outside a standard general liability pollution exclusion, which is where a separate pollution grant is usually discussed. Requirements vary by product, quantity and jurisdiction.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 11, 2026