Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

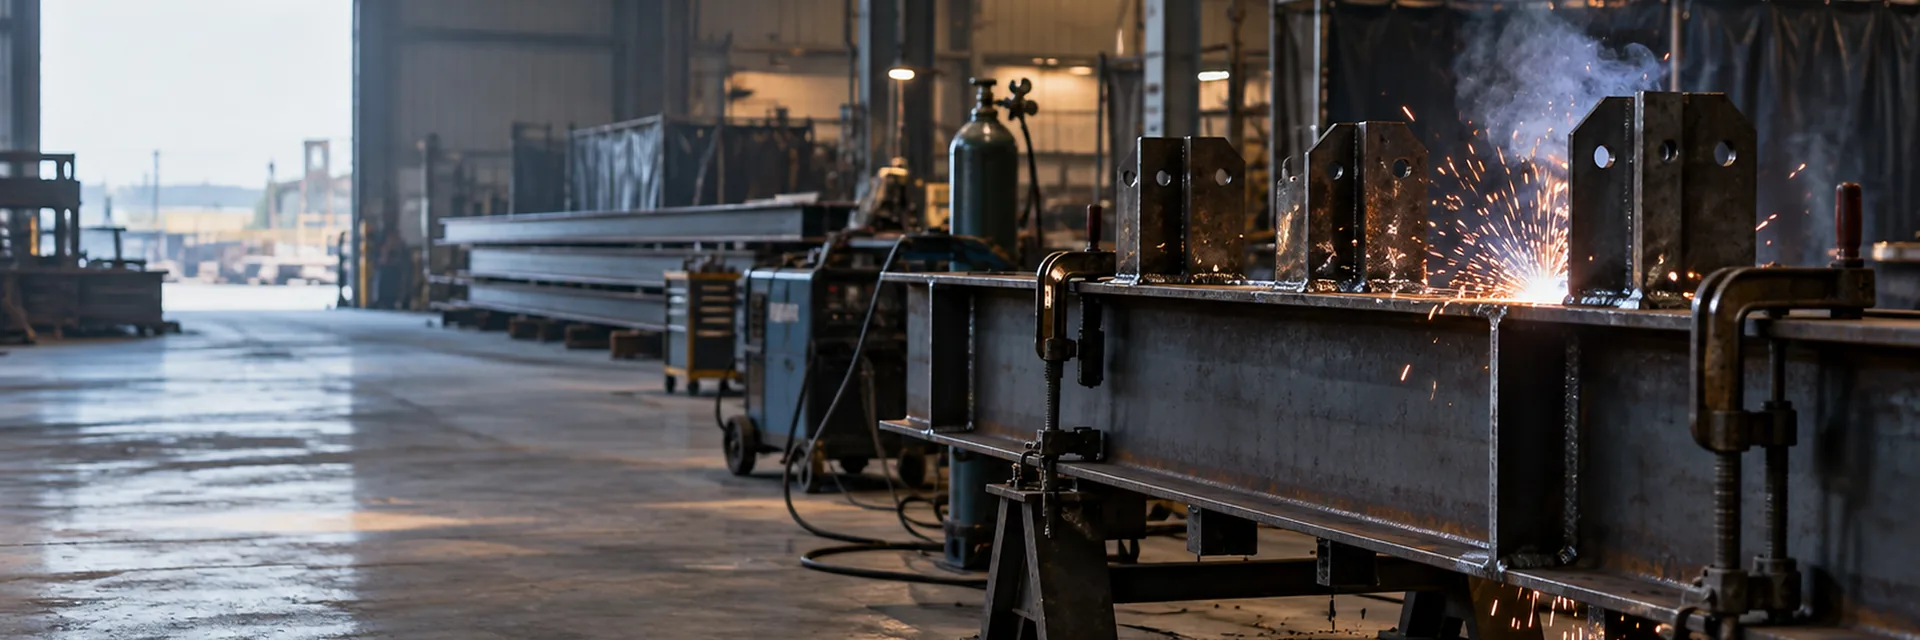
A welder joining structural steel, sparks flying from the arc — fabricated plate work and tank contractor insurance

California commercial insurance

Fabricated Plate Work & Tank Contractor Insurance California

844-97-USAVE

Storage tanks, pressure vessels and heavy fabricated plate products carry an exposure profile most general contractor policies aren't built around — products liability for the fabricated item itself, field rigging to set it, and a real pollution exposure on anything built to hold fuel, chemicals or wastewater. Gleason Insurance Brokers builds programs around that specific combination.

  • Products Liability
  • Field Installation & Rigging
  • Tank & Vessel Pollution

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Contractor Equipment / Inland MarineMobile tools, equipment and property away from premises

What it is

Inland Marine is commonly used for tools, equipment and certain mobile property that moves between locations or jobsites.

Why businesses like yours commonly carry it

Contractors frequently move tools, testing equipment and mobile machinery among jobsites.

Possible coverage gap

General Liability should not be assumed to insure the business's own tools and equipment against theft or physical damage.

Learn more about Contractor Equipment / Inland Marine
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Contractors commonly use email, electronic banking, project platforms, payroll systems and cloud document storage.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for contractors

Exposure-Dependent Coverages

Installation FloaterMaterials awaiting or undergoing installation

What it is

An Installation Floater may cover certain materials and equipment in transit, temporary storage and during installation, subject to the policy.

Why businesses like yours commonly carry it

Businesses responsible for materials before final installation commonly consider this coverage.

Possible coverage gap

A basic liability policy generally should not be assumed to cover the insured's materials against physical loss before installation is complete.

Learn more about Installation Floater
Builder's RiskProject property during construction

What it is

Builder's Risk may insure covered buildings, materials and certain project property while construction is underway.

Why businesses like yours commonly carry it

Owners, developers and contractors commonly consider it when a structure or major renovation is exposed during construction.

Possible coverage gap

Commercial Property and General Liability are not automatic substitutes for course-of-construction property coverage.

Learn more about Builder's Risk
Contractors Pollution LiabilityPollution conditions and cleanup liability

What it is

Pollution Liability may address covered cleanup costs and third-party injury or property damage arising from pollution conditions.

Why businesses like yours commonly carry it

Businesses working with fuels, chemicals, soil, water, demolition or environmental conditions may have pollution exposures.

Possible coverage gap

Standard General Liability commonly contains pollution exclusions or limitations.

Learn more about Contractors Pollution Liability
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Why tank and plate fabrication is a products-driven exposure

For many trades, the dominant concern is completed operations — whether the workmanship of an installation was done correctly. For a tank or pressure vessel fabricator, the product itself is just as often what's in question: a weld seam, a plate thickness, a fabrication defect in the vessel that was built, independent of how it was later installed. That distinction changes how the program needs to be built.

We work with tank and plate fabricators across a range of company sizes — established operations with standing fabrication capacity serving industrial, agricultural and municipal customers on the larger end, alongside smaller shops building toward that scale. Program structure, market access and current capacity all factor into how a specific account is approached, whether the business is an established operation adding crews or already running a considerably larger program. The earlier we're part of the conversation, the better we can plan around where a specific account fits.

The fabricated product itself, not just the installation, is a primary exposure
Products liability is often the dominant concern for this trade, not just completed operations
Applies to storage tanks, pressure vessels and heavy fabricated plate products
Built for established fabrication shops serving industrial and municipal customers

Field installation and rigging exposure

Setting a fabricated tank or heavy plate assembly typically involves crane or rigging work, similar in kind to structural steel but centered on vessel and tank-specific handling — confirming equipment coverage extends to this work, owned or rented, is worth doing before a larger installation rather than assumed.

Setting a fabricated tank or vessel typically involves crane or rigging work
Confirm equipment coverage extends to owned and rented rigging equipment
See our Contractor Equipment & Inland Marine guide for how this is typically addressed

Pollution exposure on tanks built to hold fuel, chemicals or wastewater

A tank fabricated or installed to hold a regulated substance — fuel, chemicals, wastewater — carries a real pollution exposure that standard general liability typically excludes. This is one of the more trade-specific reasons pollution liability coverage belongs in the conversation for this trade specifically, not as a generic add-on. See our Contractors Pollution Liability guide.

Tanks built to hold fuel, chemicals or wastewater carry a real pollution exposure
Standard general liability typically excludes pollution-related claims
This is a trade-specific reason to review pollution liability, not a generic add-on
See our Contractors Pollution Liability guide for the fuller trigger list

Workers compensation and licensing

Tank and heavy plate fabrication and installation is typically performed under a CSLB Class A (General Engineering) license or an applicable specialty classification, depending on the specific scope of work. Under SB 1455, every remaining CSLB classification will require workers' compensation regardless of employee count by January 1, 2028. See our Workers Compensation guide for the full timeline.

Typically licensed under Class A (General Engineering) or an applicable specialty classification
Covered by SB 1455's January 1, 2028 workers' comp deadline
See our Workers Compensation guide for the full timeline

Shop property and fabrication equipment

A fabrication shop carries its own property and equipment exposure — the facility, welding and forming equipment, and material and finished-product inventory — separate from whatever liability program covers field installation. See our Contractor Equipment & Inland Marine guide for how shop equipment is typically covered.

Shop facility, equipment and inventory carry their own property exposure
This is separate from the liability program covering field installation
See our Contractor Equipment & Inland Marine guide for shop equipment coverage

A realistic scenario: a weld seam issue caught before failure

A fabricated storage tank is installed at a commercial site. During a routine post-installation inspection, a weld seam issue is identified and the tank is taken offline for repair before any release or failure occurs.

Illustrative only — this describes a typical pattern, not an actual claim or a guaranteed outcome. Coverage determinations depend on the specific policy and facts involved; for a real, case-specific question, consult a licensed attorney or the appropriate authority having jurisdiction.

Fabrication defects can surface during inspection, not only after a failure
Products liability is typically what responds to a fabrication-side issue like this
The scenario above is illustrative only, not a guarantee of how any specific claim is handled

Getting fabricated plate work coverage in place

Describe the actual scope — tanks, pressure vessels, plate thickness and materials, what the fabricated product is built to hold, shop versus field work — so the program addresses products liability and pollution exposure specifically, not a generic fabrication policy.

Gleason Insurance Brokers places fabricated plate work and tank contractor coverage throughout California — call 844-978-7283 or request a quote to get started.

Describe the real scope: tanks, vessels, what they're built to hold, shop vs. field
Confirm products liability and pollution exposure are both addressed
Call 844-978-7283 or request a quote to get started

Frequently asked questions

8 questions — start typing to filter

Does general liability cover a fabricated tank that fails after installation?

This is typically a products liability question — the fabricated item itself is what's at issue. Confirming your program addresses products exposure for fabricated tanks and vessels, not just installation workmanship, matters for this trade specifically.

Do I need pollution liability if I fabricate tanks that hold fuel or chemicals?

It's worth a real conversation — standard general liability typically excludes pollution-related claims, and a tank built to hold a regulated substance carries a real, trade-specific pollution exposure. See our Contractors Pollution Liability guide.

Does equipment coverage extend to crane and rigging work for setting a tank?

It depends on the specific policy — confirming equipment coverage extends to owned and rented rigging equipment used to set a fabricated tank or vessel is worth doing before a larger installation.

Is workers compensation required for this trade if there are no employees?

Not yet in every case — but under SB 1455, every remaining CSLB classification will require workers' compensation regardless of employee count by January 1, 2028.

Does my policy cover the fabrication shop's equipment and inventory?

Not automatically under a field-focused liability policy — shop property, fabrication equipment and inventory typically need their own property or inland marine coverage.

Why doesn't general liability cover environmental or pollution-related claims?

Standard general liability policies generally exclude pollution conditions — that's specifically why pollution liability exists as a separate line, and why it's particularly relevant for anything fabricated to hold a regulated substance.

What license applies to tank and heavy plate fabrication in California?

Typically a CSLB Class A (General Engineering) license or an applicable specialty classification, depending on the specific scope of work — confirm which applies to your actual operation.

How is this different from structural steel fabrication?

Structural steel fabrication centers on crane/rigging exposure and field erection at height; fabricated plate work centers more on products liability and pollution exposure tied to what the fabricated item is built to hold. See our Structural Metal Fabrication guide for that trade specifically.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 12, 2026