
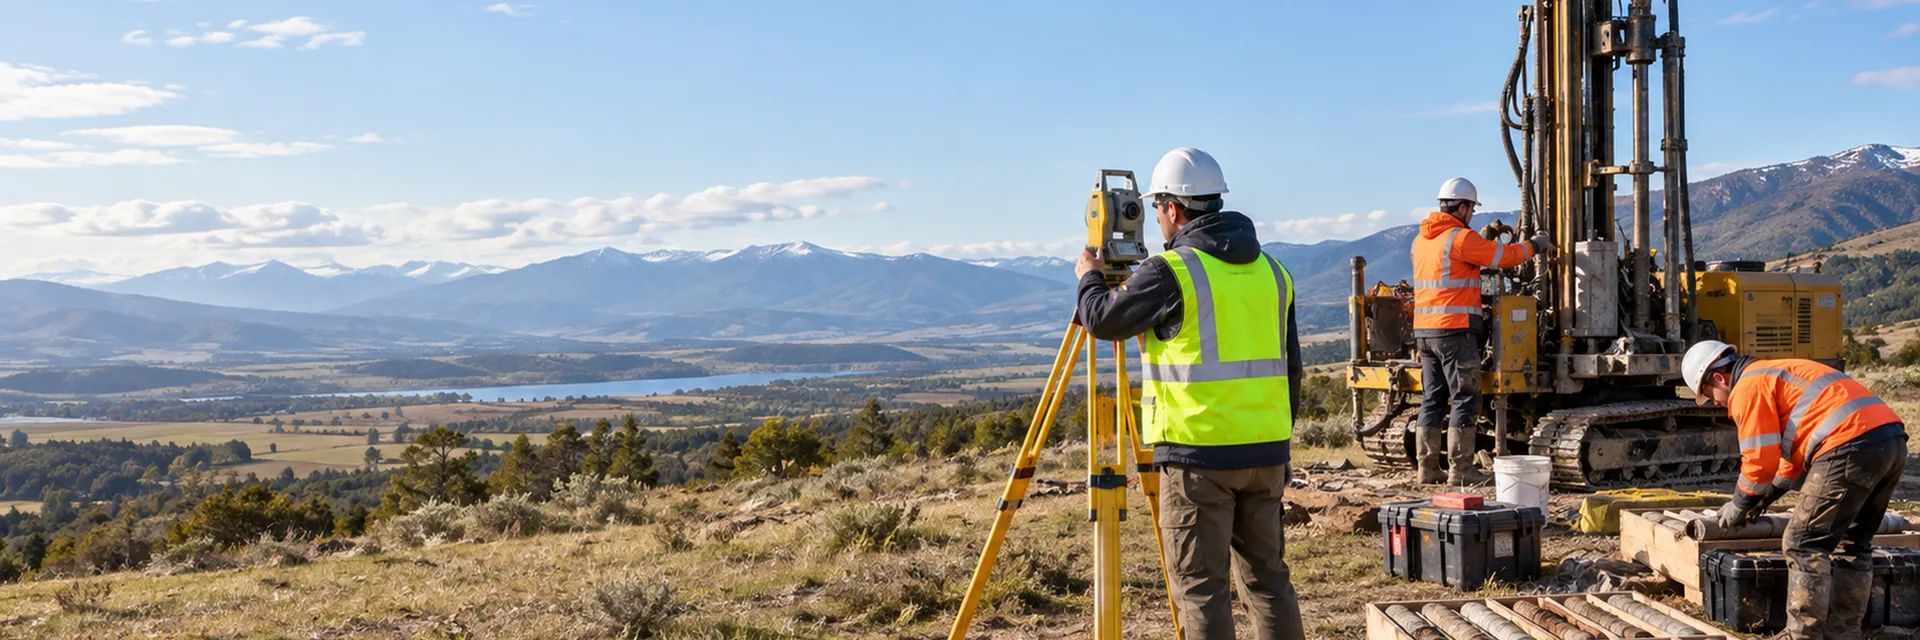


Subsurface Uncertainty
Borings sample only part of a site. Reports should state assumptions and limitations clearly.
Settlement and foundations
Unexpected movement can create claims involving slabs, structures and utilities.
Showing 1 of 4
Slopes and retaining systems
Failure severity can be significant, especially on hillside projects.
Field Observation
Compaction testing and field recommendations expand the firm's duty beyond the report.
Middle-market risk profile
Geotechnical underwriting turns on the gap between limited subsurface investigation and the very large construction decisions made from the report. Large commercial firms should clearly describe borings, lab work, foundation recommendations, slope work, liquefaction, shoring advice and construction observation. Firms whose work extends into contamination assessment and remediation oversight can see insurance for environmental engineering firms.
Contract and scope review
Contracts should avoid guarantees of subsurface conditions, define the number and location of explorations, state reliance limitations and distinguish recommendations from contractor responsibility for excavation, dewatering, shoring and means/methods.
What underwriters should receive
Useful information includes project sectors, hillside work, high-rise foundation work, seismic/liquefaction work, lab/testing revenue, construction observation, environmental overlap, largest project, claims, licensed geotechnical engineers and subcontracted drilling.
Three claim scenarios to model
Scenarios worth modeling before marketing or binding this account:
Program structure beyond E&O
Professional liability is central, with pollution professional/contractor pollution considered where environmental work overlaps. GL, auto, workers compensation, equipment coverage and umbrella support field operations.
Large-firm underwriting questions
For a larger geotechnical practice, these answers clarify slope, seismic, foundation and observation work that can drive professional liability severity and pollution considerations. Firms that also provide special inspection and materials testing during construction can review construction testing and inspection insurance.
Large-account review points
Growth can change a geotechnical account when the firm takes on taller buildings, deeper excavations, hillside development, seismic retrofit or major public infrastructure. The broker should review whether professional limits have kept pace with project value, whether construction observation has expanded, and whether subcontracted drilling creates contractual or pollution issues. For claims-made coverage, acquisitions and changes in entity structure should also be checked so prior services remain inside the intended continuity.
Frequently asked questions
8 questions — start typing to filter
Why are geotechnical claims difficult?
Subsurface conditions are inherently uncertain.
Can settlement claims trigger PL?
Potentially — if a structure settles beyond design tolerances and the geotechnical report is blamed for an inaccurate soil-bearing recommendation, that's a classic professional liability allegation.
Is pollution coverage relevant?
It can be where environmental services overlap.
Does field testing change the risk?
Yes. Boring, drilling and in-situ testing add real jobsite general liability and auto exposure on top of the firm's report-and-recommendation professional liability.
Are slope projects higher severity?
They can be — a slope-stability or landslide-related design dispute often carries higher property damage and bodily injury severity than a typical foundation report.
Why avoid guarantees in contracts?
They can create obligations beyond the professional standard of care.
Show 2 more questions
Should boring-log retention periods be confirmed?
Yes — original field data is often the firm's best defense years later when a claim alleges the original recommendation was wrong, so retention practices should match the real long-tail nature of this work.
Does construction observation carry a different exposure than the report itself?
It generally does, and the two are frequently confused in contracts. The report is a set of recommendations based on borings at particular locations on a particular date. Observation during construction puts the firm on site while the ground is open, which is both the best opportunity to catch a condition the borings missed and the point at which a court is most likely to ask what the engineer saw and said. Contracts sometimes slide from observation toward language that reads as inspection, approval or acceptance of the contractor's means and methods — a materially different undertaking, and one most professional liability forms were not written around. Reading the scope wording closely, with counsel, is the usual protection.
California · General information only, not legal advice. Requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer
Reviewed by David Gleason, Principal — November 2, 2026