
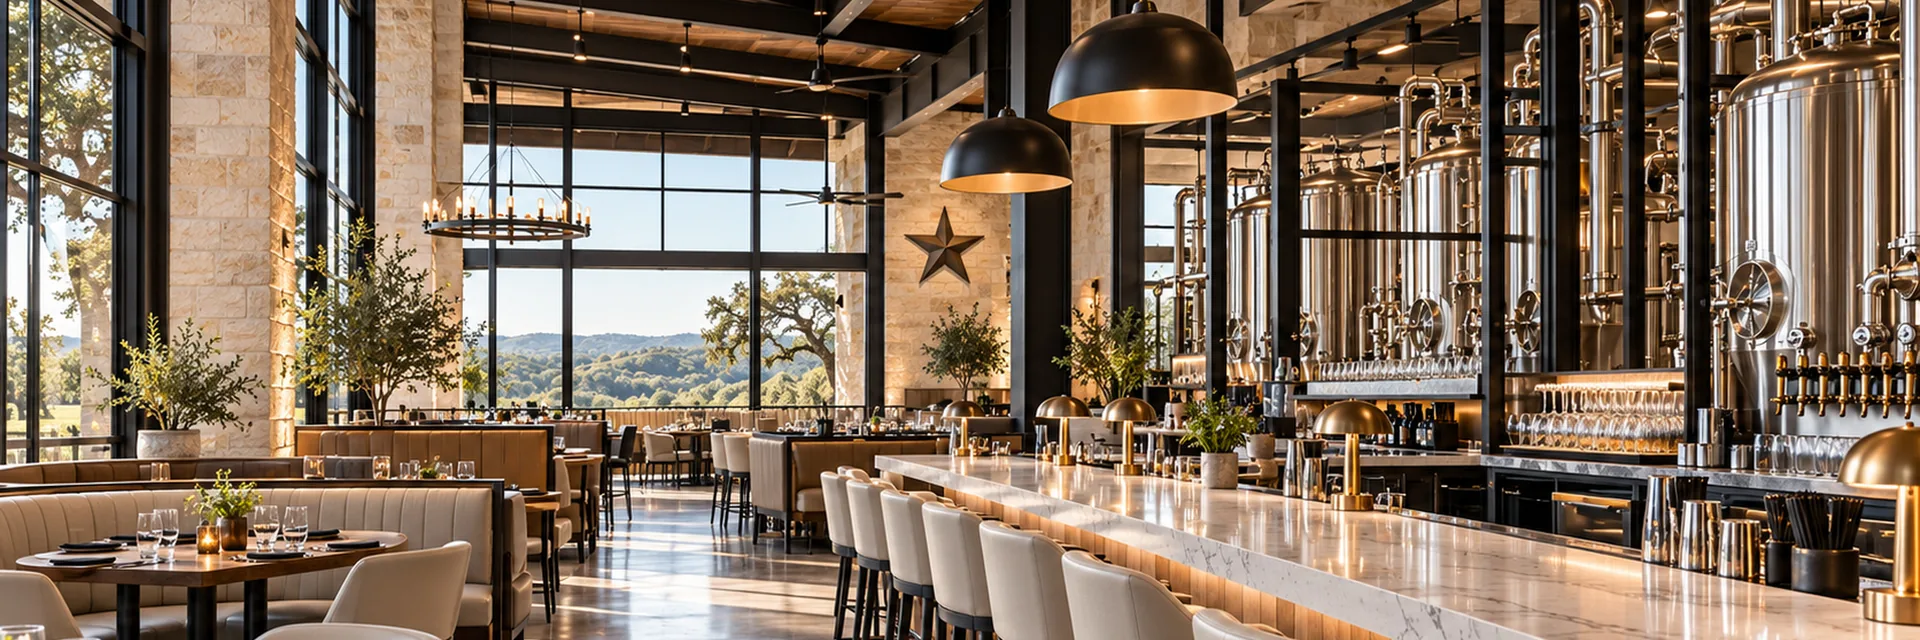
Restaurant and brewery risk in San Antonio
Restaurants and breweries in San Antonio carry exposures a generic business owner's policy often misses — liquor liability tied to alcohol service, spoilage from refrigeration failure, and equipment breakdown on kitchen and brewing equipment. Alcohol insurance is how most San Antonio operators describe it, and a River Walk location with heavy tourist bar trade carries a different profile from a neighborhood restaurant.
The starting point is general liability and property, but the food-and-beverage-specific endorsements are what actually protect the business day to day. This is exactly the spot where a generic small-business policy often doesn't hold up for a food-and-beverage business.
A concrete version of this: a River Walk-adjacent restaurant with heavy tourist foot traffic and late hours carries different overservice and security exposure than a suburban San Antonio family restaurant, even though both hold the same TABC license type. If you own the property as well as the restaurant in San Antonio, development exposures are covered on San Antonio developer and subdivider insurance.
Liquor liability and licensing
Any San Antonio restaurant or brewery serving alcohol needs liquor liability coverage, tied to licensing through the Texas Alcoholic Beverage Commission (TABC) — Texas's real state alcohol authority, separate from the trade-specific TDLR/TSBPE licenses that apply to electricians and plumbers, not restaurants.
Liquor liability sits apart from general liability as its own coverage — worth verifying it's actually included, not assumed. This applies to beer and wine service just as much as a full bar — the coverage question doesn't scale down with the type of alcohol served.
San Antonio's River Walk and downtown entertainment district carries dense tourist-driven foot traffic and real overservice/security exposure distinct from the city's suburban dining locations, and the surrounding Edwards Aquifer recharge zone is a site-selection consideration for any new construction or major tenant improvement rather than a day-to-day operating concern.
Sources for this section
- Texas Alcoholic Beverage Commission (TABC)Verified 2026-09-02
Core coverage for a food-and-beverage business
Workers compensation for a San Antonio restaurant or brewery with employees is not mandated at the state level — private employers can opt out, though most GCs and lenders require it by contract.
For a San Antonio kitchen, one refrigeration or equipment failure can represent a real loss on its own — spoilage and equipment breakdown coverage matter accordingly. A quick, explicit confirmation of both — rather than assuming either is bundled in — prevents a genuine gap.
Lease and franchise requirements
Landlords, franchisors and distribution partners in San Antonio routinely set their own insurance requirements through the lease or contract.
Before opening, confirm liability limits and additional insured requirements directly in the real lease — don't assume them from a typical landlord relationship. A landlord's requirements and a franchisor's requirements, when both apply, should be read as two distinct checklists rather than assumed to be the same. If you are opening or expanding in San Antonio, the build-out contractor's insurance matters to you too; see San Antonio contractors insurance options.
Getting coverage in place
Tell us the real picture of your San Antonio operation: alcohol service, kitchen equipment, seating capacity, and any lease or franchise insurance requirements already in place.
Restaurant and brewery coverage for San Antonio is placed as part of our broader Texas practice — call 844-978-7283 or request a quote to get started.
Health, fire and business licensing in San Antonio
Beyond TABC licensing, a San Antonio food-and-beverage operation needs a food permit from San Antonio Metropolitan Health District — Food & Environmental Health Services, fire/occupancy sign-off from the San Antonio Fire Department, and confirmation of the City of San Antonio Development Services business license office — Texas's lack of a statewide business license means this varies by city.
Workers compensation is optional for most private Texas employers (non-subscriber status) — but opting out shifts injury exposure into civil liability rather than eliminating it. Make sure your actual coverage decision is accurately reflected in the program, rather than left ambiguous.
Sources for this section
San Antonio restaurant & brewery submission checklist
Have the following ready for a San Antonio submission:
Frequently asked questions
8 questions — start typing to filter
Is workers compensation required for a San Antonio restaurant or brewery?
Workers compensation is not mandated at the state level — private employers can opt out, though most GCs and lenders require it by contract for Texas employers — apply that to your actual San Antonio staffing.
Do landlords in San Antonio require specific insurance from restaurant tenants?
Often, yes — commercial leases in San Antonio frequently require specific liability limits and additional insured status naming the landlord; read the actual lease before assuming standard coverage satisfies it.
Is TABC the right agency for a San Antonio restaurant's liquor license?
Yes — the Texas Alcoholic Beverage Commission (TABC) is the state's actual alcohol authority. TDLR and TSBPE license specific trades (electricians, plumbers), not restaurants or breweries — a distinction worth getting right.
Does Gleason Insurance Brokers write restaurant and brewery coverage in San Antonio, TX?
Yes — we're licensed in California, Arizona, Nevada, Texas and Utah, and place coverage for San Antonio restaurants, bars and breweries directly. For a San Antonio operation that usually means working through liquor liability, property and kitchen or brewing equipment, workers compensation, and the commercial auto or umbrella layers a delivery, catering or taproom operation adds — the mix depends on how the business actually runs.
Does a San Antonio restaurant or brewery need separate property coverage for the building itself?
If you own the building in San Antonio, yes — commercial property coverage protects the structure itself, separate from the business personal property, equipment and liability coverages that protect the operation.
How quickly can coverage be put in place for a San Antonio restaurant or brewery?
How fast coverage comes together depends more on submission completeness than on location — a complete, accurate submission is usually the biggest factor in turnaround. Coverage involving bonds, public works, or larger fleets typically takes longer to underwrite than a standard general liability policy.
Does Gleason Insurance Brokers need to visit my San Antonio location in person?
No — coverage is arranged remotely in the vast majority of cases, based on the information you provide. Carrier relationships and coverage expertise matter far more than a physical office location.
Does a San Antonio brewery taproom need different coverage than a restaurant?
Yes — a taproom or production brewery carries manufacturing and equipment exposure (brewing systems, CO2, kegging) beyond the liquor liability both share with a straight restaurant. Describe your actual operation type rather than a generic label.