
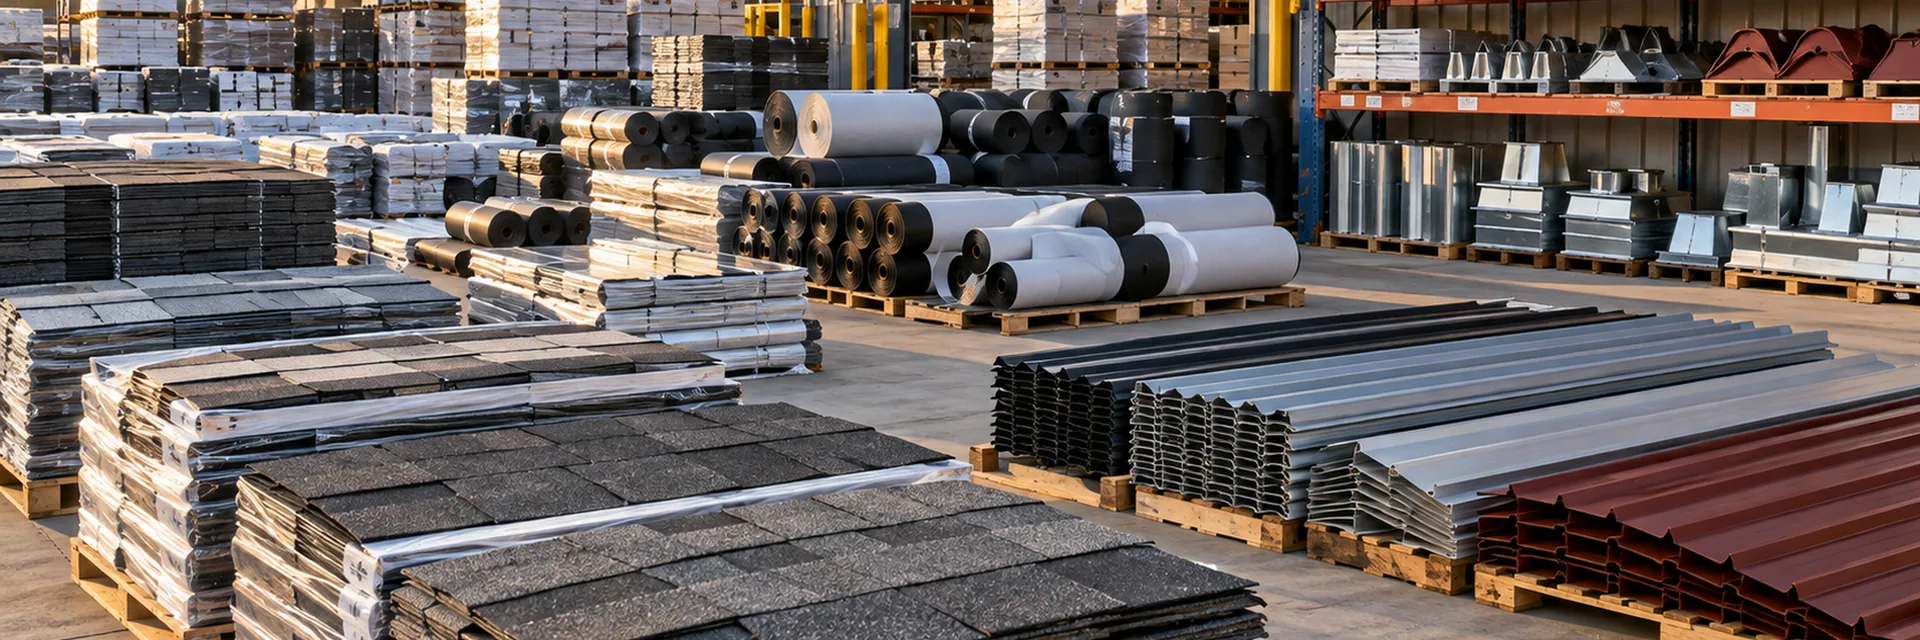


Property and fire
Large combustible stock, outdoor storage, sprinklers and wildfire exposure drive property underwriting.
Product Allegations
A supplier can be named when a roof leaks even if installation or design caused the loss.
Showing 1 of 5
Rooftop Delivery
Boom trucks and rooftop material placement add auto and loading/unloading severity.
Manufacturer Agreements
Indemnity and vendor status should be reviewed before relying on a manufacturer defense.
Middle-market account profile
For a middle-market roofing distributor, the underwriting file should quantify membrane versus shingle revenue, combustible insulation, coatings/adhesives, rooftop-delivery percentage, boom-truck use, maximum outdoor stock, seasonal inventory swings, top manufacturers and whether any material is private labeled or imported.
Coverage priorities for this niche
The strongest program coordinates warehouse/yard property with products liability, delivery auto, cargo, workers compensation and excess. Where coatings, adhesives or fuels are material, pollution should be evaluated. Cyber and crime also matter because ordering, contractor accounts and vendor payment instructions increasingly move through ERP and email.
Underwriting questions before marketing the account
Questions worth reviewing before marketing or binding this account:
Coverage gaps worth checking
Roofing distributors should confirm how the policy treats outdoor stock, property at contractor jobsites, customer-returned material, coatings or adhesives, and property on boom trucks before final delivery. The products form should be reviewed for vendor status, completed-operations allegations and any exclusions that could become important in a water-intrusion or fire claim.
What a strong submission looks like
Provide a stock-value schedule by location, peak seasonal inventory, manufacturer list, delivery fleet, rooftop-delivery percentage, boom-truck values, top contractor customers, five-year product claims and loss runs. Photos of the yard, sprinkler information, outdoor-storage controls and written loading procedures can help underwriters understand that the business is more disciplined than a generic building-material yard. For the broader picture across product lines, including products liability, fleet and yard operations, see the building material supplier risk guide.
Construction-defect tail and documentation
Roofing materials can remain part of a building for decades. When leaks appear, contractors, manufacturers and distributors can all be named before the actual cause is established. The supplier should retain purchase, lot, delivery and manufacturer records and document any product substitution. For larger commercial projects, the broker should also review whether the distributor assumes any responsibility for system selection, taper plans, rooftop placement or compatibility of components.
Frequently asked questions
8 questions — start typing to filter
Does products liability cover defective shingles?
It may respond to covered allegations, but warranty/replacement costs can be excluded.
Are rooftop deliveries higher risk?
Yes — hoisting or craning material onto a roof creates real jobsite liability exposure beyond a standard ground-level delivery.
Is roofing stock stored in the open yard automatically covered?
No — outdoor roofing material stock needs to be specifically addressed for weather, theft and catastrophe exposure, since not every commercial property form treats yard inventory the same as building contents.
Should manufacturers add the distributor as an additional insured?
That can be useful when available and appropriate.
Does cargo coverage matter on rooftop and jobsite deliveries?
Yes if the supplier retains transit responsibility.
Can coatings create pollution exposure?
Potentially — roofing coatings, sealants and adhesives can create pollution exposure from spills or improper disposal that a standard general liability policy may exclude.
Show 2 more questions
Should single-ply versus shingle products be tracked separately?
Yes — different roofing material categories carry different failure modes and claim histories, and a submission that lumps them together can understate the real product mix risk.
Does running a manufacturer's certified applicator program change the distributor's exposure?
It can, and in a way that is easy to miss, because the distributor's role moves from supplying material to standing somewhere near the warranty. Certified applicator programs commonly involve the distributor in training, in approving or recommending contractors, and sometimes in inspecting completed work before a manufacturer's system warranty is issued. Each of those is a service rather than a sale. Where a roof fails and the warranty is declined, a building owner who was pointed at a contractor by the distributor may name the distributor too. Underwriters generally want to know whether the firm recommends installers, whether it inspects, and what the paperwork says about who is responsible for what.
California · General information only, not legal advice. Requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer
Reviewed by David Gleason, Principal — November 2, 2026